Category: Tech

  • Alphabet Q3 2026 Earnings: Is Google’s Business Going Down?

    Alphabet Q3 2026 Earnings: Is Google’s Business Going Down?

    Alphabet Q3 2026 earnings gave investors a strange mix of signals. Revenue jumped 25%. Cloud revenue doubled. Yet the stock fell about 13% in two days. It closed at $279.84 on October 30, down from $323.32 on October 27.

    So, is Google’s business going down? By the numbers, no. The core business is growing faster than it has in years. But cash flow turned negative, spending keeps climbing, and AI is changing how Google earns money from each search.

    Key takeaways from Alphabet Q3 2026 earnings

    • Revenue grew 25% to $127.6 billion.
    • Google Cloud revenue grew 103% and its backlog hit $561 billion.
    • EPS missed, mostly because of an investment loss.
    • Free cash flow was negative for the second quarter in a row.
    • Search is changing, and each AI question earns less than the old results page.
    • Analysts cut price targets, but most still rate the stock a buy.

    What does Alphabet do?

    Alphabet is the parent company of Google. Most of its money still comes from ads on Google Search, YouTube and the ad network.

    Its second engine is Google Cloud. Cloud rents computing power, AI tools and Google’s own AI chips, called TPUs, to businesses. The third piece is Other Bets, a group of long shot projects. Waymo, the self driving car unit, is the best known.

    Alphabet Q3 2026 earnings at a glance

    Revenue came in at $127.6 billion, up 25% from $102.3 billion a year earlier. Operating income rose to $40.6 billion, and operating margin edged up to 32%.

    Growth is also speeding up. Here is the year over year growth by quarter:

    • Q3 2025: up 16%
    • Q4 2025: up 18%
    • Q1 2026: up 22%
    • Q2 2026: up 24%
    • Q3 2026: up 25%
    1 revenue growth

    Why did Alphabet’s EPS miss?

    The EPS miss was the headline that scared investors. EPS was $2.12, well short of the roughly $3 analysts expected, and net income fell about 25% to $26.2 billion.

    However, the cause was not the core business. Other income swung from a gain of $12.8 billion a year ago to a loss of $8.2 billion this quarter. Reports tie an unrealized loss on Alphabet’s SpaceX stake to about $0.55 per share. Alphabet itself did not name the investment.

    Add that $0.55 back and EPS is about $2.67. That is still below expectations, so it was a real miss. It just was not as bad as the headline.

    Here is the EPS history:

    • Q3 2025: $2.87
    • Q4 2025: $2.82
    • Q1 2026: $5.11
    • Q2 2026: $9.11
    • Q3 2026: $2.12

    Q1 and Q2 were inflated by big paper gains on investments. Q3 went the other way. Therefore, operating income is the better guide, and it rose about 30%.

    2 eps growth

    Is Google Search going down? How AI changes Google’s business

    Many people assume Google Search is fading because users now ask AI. The data says something different.

    CEO Sundar Pichai said Search query growth was the strongest in five years. Also, Search and other revenue rose 12% to $63.35 billion. People are not leaving Google. They are changing how they ask.

    Users now type full questions and expect an answer, not ten links. AI Mode in Search has passed one billion monthly users, and the Gemini app has reached one billion users.

    The catch is money per question. Management said AI Mode monetizes at a lower level than traditional search. As a result, Search revenue missed estimates for the second quarter in a row. Google’s business is not shrinking, but each AI answer earns less than the old results page, at least for now.

    Advertisers now want to be recommended

    This is the biggest shift in the ad business. Before, a brand paid to rank on a results page. Now brands want the AI to name them inside the answer.

    That has created two separate budgets:

    • Paid placement. Google is expanding ads inside AI Mode worldwide, and it made its biggest update to product listing ads in a decade.
    • Earned visibility. Brands also invest in making their content easy for AI to read and cite. This is called generative engine optimization, or GEO. It is a separate investment from buying AI ads.

    Rivals are in the game too. OpenAI began showing ads in ChatGPT on February 9, 2026, with more than 600 advertisers signed up. Still, agency executives are not yet convinced brands need dedicated AI visibility budgets. The spending is real but early.

    For Alphabet, the bull case is that these ads still run on Google’s ad system, so Google gets paid either way. The bear case is that AI answers must earn as much per question as the old results page did.

    Google’s data is the quiet advantage

    AI answers still depend on information that people created. Google holds one of the largest collections of it: a web index built over decades, plus YouTube, Maps, Shopping data and years of feedback on what people click and trust.

    There are two limits. First, rival AI models also learn from the open web, so the data is an edge, not a lock. Second, publishers want to be paid or sent traffic. Five French publisher groups recently filed a complaint with the EU over AI Overviews. That is a legal risk to watch.

    Google Cloud: the growth engine behind Alphabet Q3 2026 earnings

    Google Cloud is the star. Cloud revenue was $30.71 billion, compared with $15.16 billion a year ago. That is a 103% jump. Growth has sped up every quarter this year: 34%, then 48%, 63%, 82% and now 103%.

    Profit is growing too. Cloud operating income rose from $3.6 billion to $11.1 billion in a year. That works out to a margin of about 36%.

    The best forward signal is the Google Cloud backlog. It reached $561 billion in Q3. It was $155 billion a year ago. Backlog is contracted revenue that Alphabet has not yet recognized. Management said earlier in the year that just over half of it should turn into revenue within 24 months.
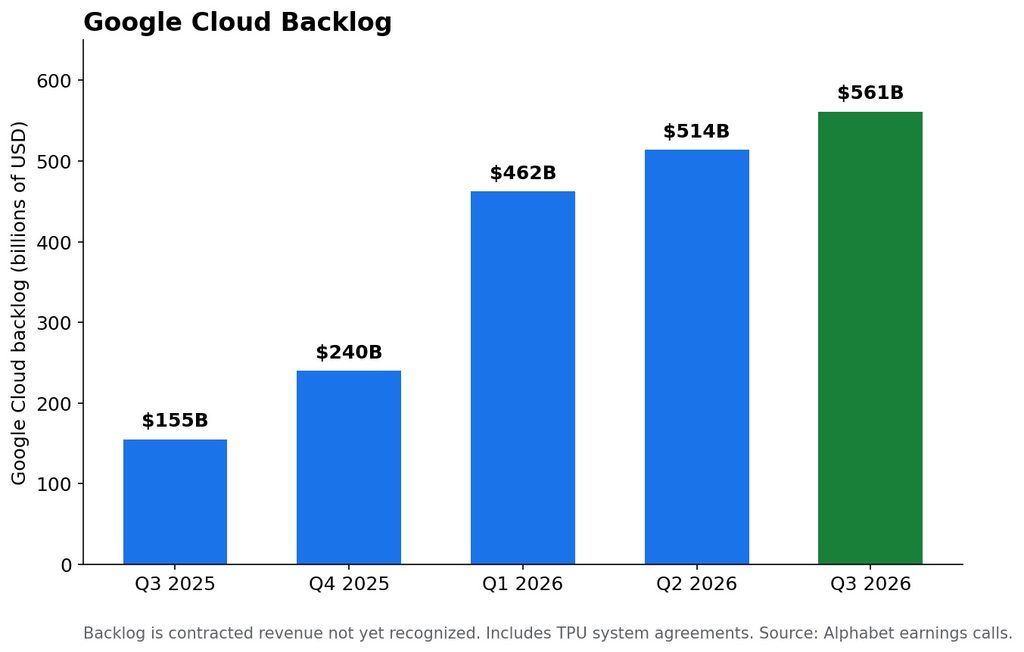
    3 cloud backlog

    Cash flow and capex: the weak spot

    Profit is up, but cash is not. Operating cash flow fell 13% to $42.3 billion, while spending on property and equipment more than doubled to $51.4 billion. That left free cash flow at negative $9.1 billion.

    This is the second negative quarter in a row. Trailing twelve month free cash flow dropped 73% to $19.7 billion. So cash flow did not improve. It got worse.

    One small positive: over nine months, operating cash flow is still up 13%. Part of the Q3 drop came from working capital, including a big jump in inventory.

    Capex keeps rising. It went from $24.0 billion in Q3 2025 to $51.4 billion in Q3 2026, which is about 40% of revenue. Full year 2026 guidance stayed at $195 to $205 billion, and management expects spending to rise significantly in 2027. To hit that range, Q4 would need $63 to $73 billion. That is a calculation from the guidance, not a company figure.

    4 cash flow

    How is Alphabet funding the spending?

    Alphabet is not close to running out of money. However, it is now paying for growth with outside capital.

    • Cash and debt. Cash and securities were $265.1 billion, and long term debt rose from $46.5 billion to $125.1 billion in nine months.
    • Fundraising. Over nine months, Alphabet raised about $142 billion from debt, new shares and preferred stock. In Q3 alone it sold $28.7 billion of notes and $12.4 billion of stock.
    • No buybacks. Alphabet bought back no shares this year, and the share count is up 1.7%.

    Here is a rough illustration. If operating cash flow stays near $42 billion and Q4 capex lands in the guided range, the gap could be $21 to $31 billion in Q4, before dividends. At a gap near $30 billion a quarter, $265 billion would cover about eight quarters on paper. That is a back of the envelope figure. It ignores new borrowing and bigger 2027 capex.

    As for profit, Alphabet is already profitable. The real question is when free cash flow turns positive again. Management has said it will stay under pressure while it invests in AI infrastructure, and there is no date.

    Technology roadmap, is Google on track?

    Short term. Alphabet just launched Gemini 4 Argon and Carbon. Pichai said they lead at the frontier, and model APIs now process nearly 32 billion tokens per minute, more than four times last year. Alphabet also sells TPU chip systems directly, which is a new revenue line.

    Long term. The bigger bets are Waymo, Google’s own chips and AI inside every product. Other Bets still loses money. It lost $2.04 billion this quarter, versus $1.4 billion a year ago.

    The goal. Pichai calls it a full stack approach. Alphabet builds the chips, the models, the cloud and the products people use, all in one company.

    On track? On tech and Cloud, yes. Cloud growth has sped up five quarters in a row, and Gemini usage is exploding. On cash discipline, less so. Capex guidance was raised twice this year, and Search missed estimates again.

    Guidance: what does Alphabet expect?

    In the short term, 2026 capex guidance is $195 to $205 billion, unchanged. Alphabet does not give revenue or EPS guidance. More Q4 detail comes on the next call.

    In the longer term, capex rises significantly in 2027. The CFO also said more TPU system revenue is expected in 2027. The $561 billion backlog is the best signal of future revenue.

    Fundamental check: is Alphabet fairly priced?

    Headlines can mislead here, so start with the earnings. Alphabet trades at a P/E of about 14.6. That looks cheap. But reported EPS is full of investment gains. In Q2 alone, gains added $6.26 per share.

    I stripped those swings out. Q1 core EPS was roughly $2.76, Q2 was roughly $2.60 to $2.75, and Q3 is about $2.67. With Q4 2025’s $2.82, trailing core EPS is about $10.90. That puts the stock at roughly 26 times core earnings. These are my estimates.

    A few more valuation angles:

    • PEG ratio. The reported PEG is 0.94. On my core numbers it is about 0.85. Both are under 1.
    • Enterprise value. It is about $3.28 trillion, or about 7 times trailing revenue and 21 times trailing operating income.
    • Free cash flow yield. It is only about 0.6% of market cap, because of the capex bill.

    Business quality is high. Trailing operating margin is about 33%. My EBITDA proxy is up about 33% year over year. The balance sheet is strong, with about $140 billion of net cash. The current ratio is 2.72.

    The weak points are the debt trend, the paused buybacks and the negative free cash flow. As a rough payback check, Cloud earned about $7.5 billion more operating profit this quarter than a year ago. Times four, that is about $30 billion a year, against about $160 billion of capex over twelve months. It is not a true return on capital, but it shows payback takes time.

    So the stock is not a deep bargain on core earnings. It is a fair price for a fast growing, high margin business.

    What is Alphabet’s moat?

    Five things protect this business:

    1. Distribution. Search, Chrome, Android and YouTube reach billions of people daily.
    2. Own chips. TPUs lower Alphabet’s cost to run AI and now bring in revenue from other customers.
    3. Contracted demand. A $561 billion backlog means customers have already committed.
    4. Full stack. Few rivals own the chips, models, cloud and consumer products at once.
    5. Data. Decades of web, video, map and shopping data, plus user feedback on what works.

    What could go wrong?

    • Cash burn. Free cash flow is negative and capex keeps rising.
    • Dilution. New shares and new debt are paying for the buildout.
    • Search monetization and publisher pushback. AI Mode earns less per query, and publishers are fighting over how AI uses their content.
    • Customer concentration. UBS projections put OpenAI and Anthropic at 27% of Cloud revenue in 2026 and over 48% in 2027. That is a projection, not a reported number.
    • Noisy earnings. Investment gains and losses make reported EPS jump around.

    GOOGL price target after Alphabet Q3 2026 earnings

    Wall Street cut targets after the report, but most analysts stayed positive. The consensus target is $410.46, with five Strong Buy ratings, 46 Buy ratings and five Hold ratings.

    6 price targets

    FAQ: Alphabet Q3 2026 earnings

    Is Google’s business going down?
    No. Revenue grew 25% and operating income grew about 30%. However, free cash flow is negative, and AI is changing how Search earns money.

    How much did Alphabet make in Q3 2026?
    Revenue was $127.6 billion, operating income was $40.6 billion, and net income was $26.2 billion.

    Why did Alphabet stock fall after earnings?
    EPS missed, free cash flow turned negative again, and capex keeps rising. Search also missed revenue estimates for the second quarter in a row.

    What is the Google Cloud backlog?
    It is contracted revenue not yet recognized. It reached $561 billion in Q3 2026.

    What is the GOOGL consensus price target?
    It is $410.46, according to MarketBeat as of October 30, 2026.

    The bottom line: is Google’s business going down?

    Alphabet Q3 2026 earnings show a strong business with a costly habit. Revenue, operating income and Cloud all grew fast. Cash flow, EPS and the stock did not.

    Google’s business is not going down. It is changing. Search usage is growing, but AI answers earn less per question for now. Cloud is doubling, but capex is outrunning cash. The price asks you to believe Cloud profits will catch up with the spending.

    The next few quarters come down to one question: does Cloud profit growth catch up with the cost of building all that capacity?

    Disclosure: The author holds a long position in $GOOGL stock at the time of writing

    Related articles:

    SpaceX Stock Analysis: Reusable Orbital Launch and Starlink Broadband: Reports tie Alphabet’s Q3 EPS hit to an unrealized loss on its SpaceX stake, so this gives readers the background.

    CoreWeave’s $104B Backlog and the Path Through the Refinancing Window: It covers the same trade off as Google Cloud’s $561 billion backlog, where big contracted demand meets heavy funding needs.

    Nvidia’s CEO Says Memory and Neocloud Demand Are Fine. Here Is What Investors Should Weigh: This is the wider AI infrastructure demand story behind Alphabet’s capex.

    NBIS Stock Analysis: Is Nebius Worth Buying in 2026?: It is another AI cloud name, useful for comparing against Google Cloud.

    S&P 500 Valuation 2026: Room to Run or Topping Out?: It gives market wide valuation context for a mega cap like Alphabet.

    Celestica (CLS): The Company Solving the Demand for AI Compute Systems: It looks at the suppliers who benefit from the $195 to $205 billion capex Alphabet plans.

    Sources:

  • Nvidia’s CEO Says Memory and Neocloud Demand Are Fine. Here Is What Investors Should Weigh

    Nvidia’s CEO Says Memory and Neocloud Demand Are Fine. Here Is What Investors Should Weigh

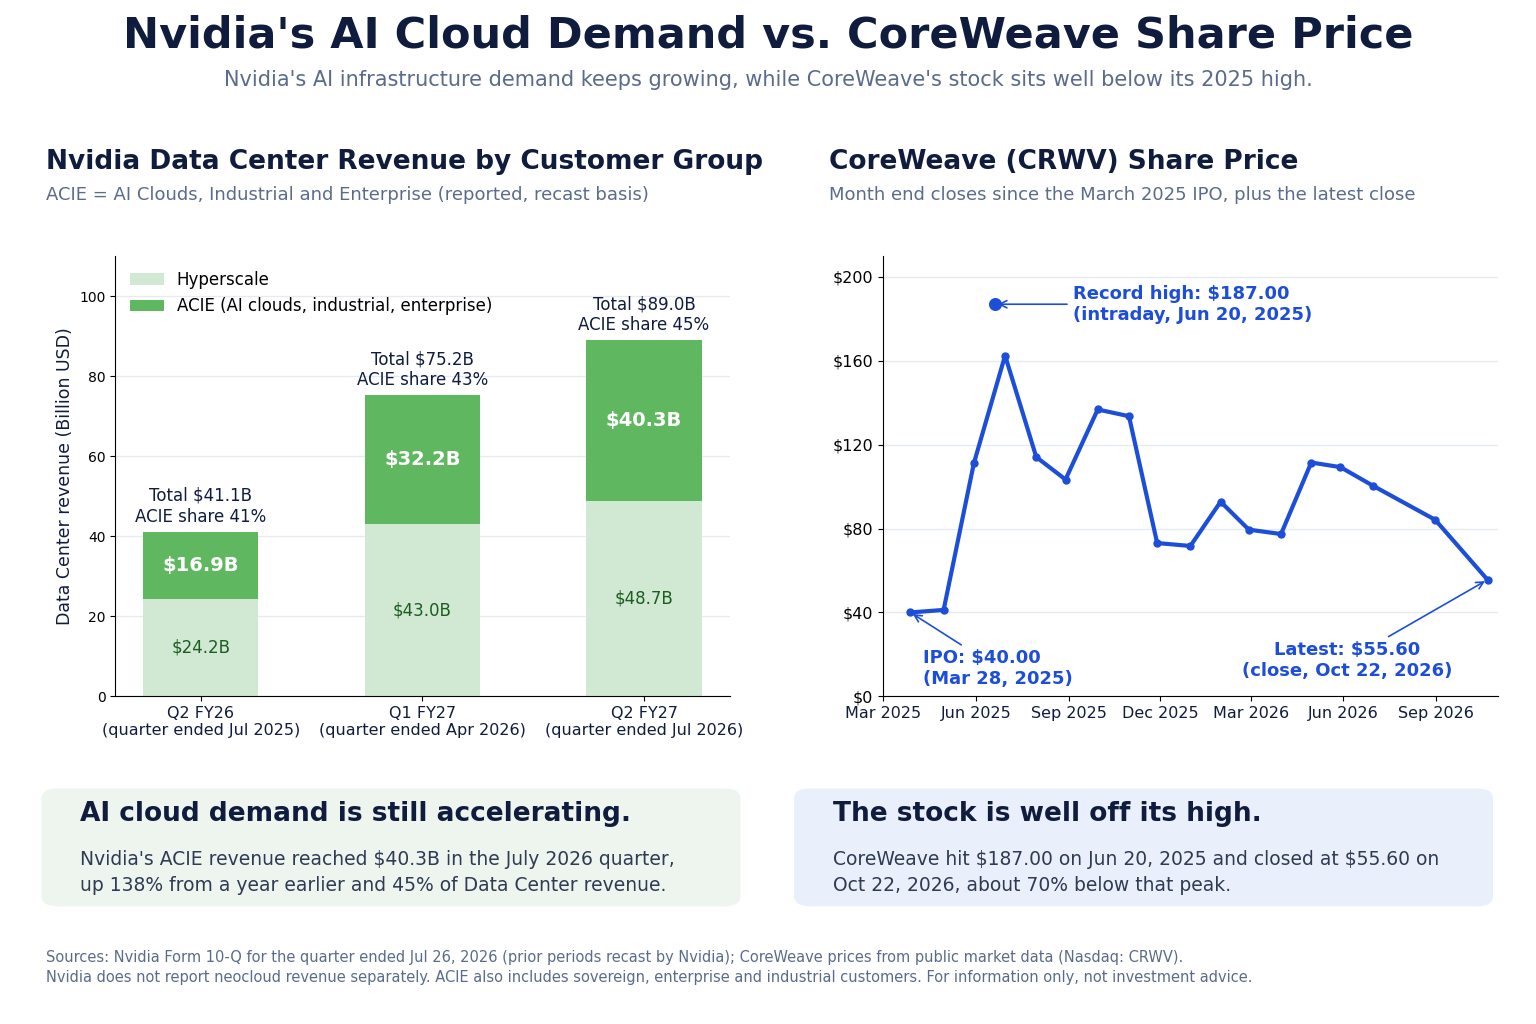
    Nvidia neocloud demand is “off the charts,” according to Jensen Huang, who spoke with CNBC at GTC Berlin on Thursday. He also took on fears of a memory glut. His message on both was that demand is strong, though investors should remember he runs the company selling into both markets.

    Memory: no glut in sight

    Huang said a surplus of memory supply is unlikely by 2029, despite a sell off in memory stocks over the past week. SK Hynix, Samsung and Micron took a hit after a South Korean opinion column warned of a “red ocean” of excess supply, meaning tougher competition and slimmer profits. The selloff was also driven by China’s CXMT announcing a new design architecture that could lead to greater efficiencies. Nvidia’s Jensen Huang says he sees no sign of a 2029 memory glut: ‘You can always use more’ +2

    Huang’s answer was simple: memory is something you can always use more of. He said HBM will stay in use for many years and that Nvidia plans to keep using large amounts of LPDDR, the memory type found in phones, in data centers. He said that LPDDR approach delivers performance at half the energy per unit of work of any alternative. Jensen Huang pushed back on 2029 memory glut fears amid stock selloff +2

    Asked about CXMT specifically, he said Nvidia is open minded and noted that nearly the whole world works with Chinese companies somewhere in the supply chain. He also said U.S. regulations have accelerated China’s efforts to build domestic chips.

    The takeaway for investors: a glut call is really a supply call. Huang is a big buyer vouching for demand, but the bear case rests on new capacity, including from Chinese producers. Memory has always been a cyclical business, and one CEO’s forecast three years out does not change that.

    Nvidia neocloud demand: money is the bottleneck

    On the neocloud side, Huang said the demand for neoclouds is off the charts and their capabilities are extraordinary, but the working capital to fund that growth is missing. In his words, the demand for capital is much greater than its availability, and he expects that to get solved. He framed it as a scarcity of capital rather than weak demand, because so many AI sectors are competing for the same money. Nvidia’s Jensen Huang Wants AI Chips To Be A ‘Financeable Asset,’ Says Neocloud Demand Is ‘Off The Charts’ +2

    He also pointed to a second constraint. Power is a limiting factor, especially in Europe where electricity costs more, and he argued scarce power should go to companies like Nebius and Mistral if they are to scale.

    The market was not reassured. Ahead of Thursday’s open, Nebius fell 3.6%, CoreWeave slipped 4%, and Iren and Applied Digital each dropped nearly 4%. CoreWeave shares are down 50% over six months, even as Nvidia invested another $2 billion in the company in January.

    Huang’s bigger pitch is about financing itself. He said Nvidia is trying to establish its compute as a financeable asset, because its residual value is durable enough to become an asset class. If lenders buy that, the capital gap narrows. If they do not, the gap stays.

    The other side of the story

    Critics see a circular loop. The Information reported that Nvidia is increasingly acting as lender and backstop for the neoclouds that buy its chips, that its AI Compute Partnership is being restructured after established neoclouds such as Nebius pushed back, and that its credit default swap spreads have roughly doubled in recent months, though its credit rating remains near the top.

    One widely shared critique compares Nvidia to GE Capital rather than Enron, arguing that its customers are driven by fear of missing out and that its growth requires perpetual acceleration. That is an opinion piece, not a finding, but it names the risk. Huang himself said in April that these neoclouds would not exist without Nvidia’s support.

    What I am watching

    First, whether lenders accept GPUs as collateral worth financing, since that is the stated fix for the capital gap. Second, credit signals around Nvidia and the neoclouds, such as spreads and bond pricing, which often move before equities do. Third, how fast new memory supply actually arrives compared with what Huang expects.

    Huang can be right about demand and investors can still lose money if the financing breaks first. Strong demand does not guarantee that every company serving it survives its debt.

  • CoreWeave’s $104B Backlog and the Path Through the Refinancing Window

    CoreWeave’s $104B Backlog and the Path Through the Refinancing Window

    The AI infrastructure market is showing a split. Equity investors are focused on hypergrowth, while credit markets are pricing in near term financing costs. For CoreWeave (CRWV), a leader in the specialized AI cloud space, that gap raises a clear question: how does a company with massive demand turn it into financial strength?

    The answer is already visible. CoreWeave reported a $104 billion contract backlog, and the company has several practical tools to convert that backlog into a stronger balance sheet.

    1. Why CoreWeave Demand Is Not the Problem

    Few companies can say their growth is already contracted years ahead.

    • Record backlog: Contracted revenue reached $104 billion at the end of Q2, with more than $25 billion in new commitments added shortly after.
    • Capacity nearly sold out: Management says capacity through 2027 is almost fully booked, and customers are already reserving space for 2028 to 2030.
    • Top tier customers: Multibillion dollar commitments from Microsoft, Meta, and OpenAI validate the demand.

    When customers line up years in advance, a company has real leverage in how it structures its financing.

    2. Turning Backlog Into Cash Flow

    Multi year compute contracts turn into revenue gradually, over 3 to 5 years, as data center capacity comes online. As more capacity goes live, the revenue base grows and the financing picture improves with it. The $51.9 billion in total debt and lease obligations funded the buildout of that capacity, and the contracts behind it support the repayment.

    3. The CoreWeave Toolkit for the 2026 to 2027 Window

    CoreWeave has several ways to bridge the gap between near term maturities and long term contract payoffs:

    • Customer prepayments: Large upfront cash from customers, a model peers like IREN use, can fund buildouts without adding more high yield debt. With demand this strong, CoreWeave is well positioned to ask for it.
    • Nvidia ecosystem support: As a key hardware partner, Nvidia has a stake in a healthy GPU market, so collateral support or equity linked financing is a realistic option.
    • Equity and convertibles: Share offerings or convertible bonds dilute existing holders, but they offer a direct way to pay down senior debt and reduce interest costs.
    • Refinancing on better terms: As contracted revenue turns into reported cash flow, lenders get more evidence that the backlog is real, which can open the door to lower cost debt over time.

    The $10.6 billion due over the next 24 months is sizable, but it sits against a $104 billion backlog.

    4. Looking at CoreWeave Through a Fundamental Lens

    Credit matters, but it helps to separate two kinds of problems.

    Credit is something every company has to manage. It is a controllable element, handled through refinancing, prepayments, equity raises, and better contract terms. A business with strong demand has more ways to fix it than a business without demand.

    What actually breaks a long term investment case looks different:

    • Fraud or accounting problems: Trust in the numbers is gone.
    • Revenue and growth rolling over: Demand is fading.
    • Earnings per share falling quarter after quarter: The business is getting weaker, not just more expensive to finance.
    • Rising debt with no progress: More borrowing, but no new capacity, customers, or revenue to show for it.

    Right now, none of these is the story. Revenue is growing, backlog is expanding, and new debt is going toward capacity that customers have already contracted for.

    The current credit stress also looks more like a macro problem than a company problem. High inflation and high interest rates put pressure on any high growth company that funds expansion with debt. That pressure tends to ease as rates settle, and it hits fast growers hardest before the cash flows arrive.

    So I do not see this as the time to sell. The signals that would change my mind are about the business itself, not the temporary cost of financing it.

    5. Why the Market Is Still Moving in CoreWeave’s Favor

    CoreWeave is part of a broader shift in AI cloud infrastructure, where scarce capacity is gaining value.

    Leveraged neoclouds (e.g., CoreWeave)Vertically integrated infrastructure (e.g., NBIS, IREN)
    StrengthFast deployment and deep customer relationshipsDirect control of power and data center capacity
    Growth driverHyperscalers leasing capacity as fast as it comes onlinePremium pricing on scarce megawatt capacity
    Next stepConvert backlog into cash flow and lower financing costsScale within grid interconnection timelines

    Both models benefit from the same trend: demand for compute is outrunning supply.

    The Bottom Line

    Demand for CoreWeave is clear, and hyperscalers are leasing capacity as fast as it can be deployed. A $104 billion backlog gives the company real negotiating power with customers, partners, and lenders.

    Credit is a real element to watch, but it is a solvable one. The things that would make me sell are fraud, shrinking revenue and growth, steadily falling earnings, or more debt without progress. Until I see those, I treat the credit stress as a high rate environment problem, not a broken business.

    For long term investors, the key things to watch are how much of the backlog converts into revenue, whether customer prepayments become part of new deals, and how the refinancing window plays out. If CoreWeave executes, the same backlog that looks heavy today could become the foundation of a much stronger balance sheet.

    Disclosure: The author has no position in $CRWV and no commercial relationship with the company

    Sources: CoreWeave

  • Celestica (CLS): The Company Solving the Demand for AI Compute Systems

    Celestica (CLS): The Company Solving the Demand for AI Compute Systems

    Celestica is not a name most people talk about at dinner. But if you follow AI stocks, it should be on your list. The latest numbers are strong, and the story has some twists too, including a big share sale in August.

    cls rack

    What does Celestica do?

    Celestica is a Toronto based company that designs and builds hardware for data centers. Its biggest unit, Connectivity and Cloud Solutions, covers networking switches, AI compute systems, and storage for the largest cloud companies. The smaller unit, Advanced Technology Solutions, serves aerospace, defense, industrial, health tech, and capital equipment customers.

    Think of it as the company that builds the pipes and racks inside AI data centers.

    celestica revenue growth

    Celestica’s latest quarter

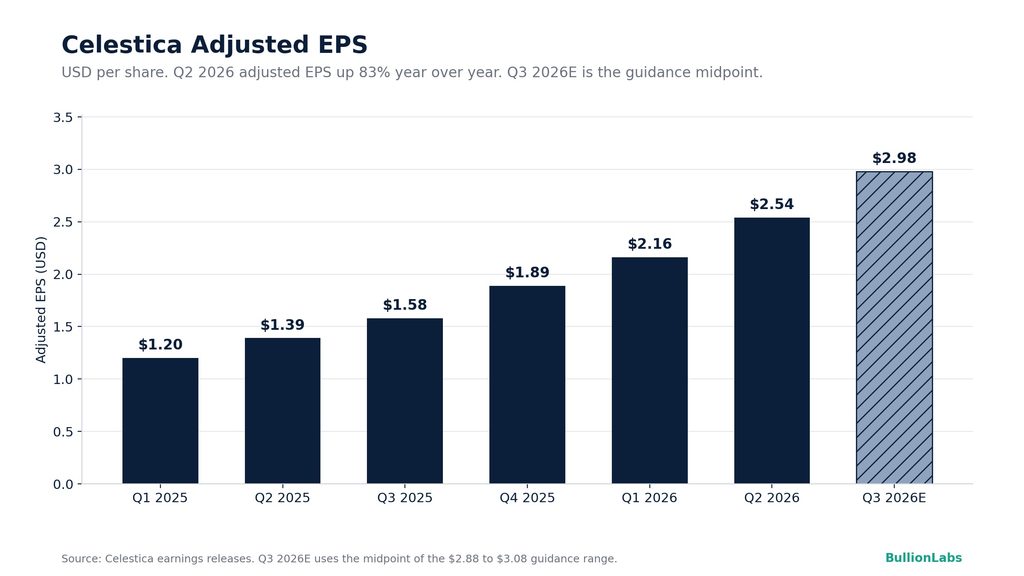
    Celestica reported Q2 2026 results on July 27. Revenue hit $4.70 billion, up 62% from $2.89 billion a year earlier. Q1 revenue was $4.05 billion, so revenue grew about 16% from one quarter to the next.

    celestica eps growth

    Earnings per share followed the same path. Adjusted EPS was $2.54, compared to $1.39 a year ago. In Q1 it was $2.16, so EPS grew roughly 18% quarter over quarter and 83% year over year. GAAP EPS was $3.17, but part of that came from a swap gain, so the adjusted number is the cleaner one to watch.

    celestica cash flow

    How is the cash flow?

    It improved. Cash from operations was $410.9 million in Q2, up from $152.4 million a year ago. Free cash flow was $147.1 million, up from $119.9 million. It did not rise as fast because spending on equipment jumped.

    For the year, management now expects free cash flow of $600 million, up from $500 million.

    Celestica spending, funding, and cash runway

    Growth costs money. Celestica plans about $1 billion of capital spending in 2026 and is expanding sites in Thailand, Japan, and Texas. A rough placeholder for 2027 is $1.5 billion. Spending is already running at about $260 million per quarter.

    At the end of June, cash was $535.7 million, against roughly $810 million of borrowings. Then came the big move. In August, Celestica priced an equity offering of 9,677,419 shares at $310 each, for about $3 billion. The money is meant for working capital and capital spending.

    My math: the raise roughly covers the planned 2026 and 2027 spending combined, so cash runway is not a worry. The cost is dilution of about 8% in share count. The stock dropped after the news.

    Technology: near term, long term, and the goal

    Short term, the story is faster networking. The CEO said there are 10 active 1.6T programs, while 800G and 400G products keep growing. The 1.6T programs begin production in the second half of 2026.

    Long term, the bigger prize is AI compute. Management pointed to new programs with OpenAI, AMD, and Broadcom, including custom accelerator racks. Management expects these to scale in 2027.

    The goal is clear. Celestica wants to be a core design and build partner for AI data centers, not just a contract assembler. The CEO said capacity planning is already set for 2026 and 2027.

    Is it on track? So far, yes. Q2 revenue and adjusted EPS both landed above the high end of guidance. Back in October 2025, the 2026 outlook was $16 billion in revenue. It is now $20.5 billion. The main limit is not demand. It is component supply.


    Supply is the part to watch. Celestica says demand is not the problem, parts are. AI compute systems need a lot of memory, and memory makers know it. Many of them are now signing long term agreements to lock in customers for years. That shows how tight supply is across the AI chain. It also explains why Celestica has to plan its capacity so far ahead.

    Guidance

    Near term, Q3 revenue is guided to $5.25 billion to $5.55 billion, with adjusted EPS of $2.88 to $3.08.

    celestica outlook backlog

    For the full year, the outlook is $20.5 billion in revenue, $11.30 in adjusted EPS, and an 8.4% adjusted operating margin. That implies growth of 65% in revenue and 87% in EPS.

    Longer term, management expects 2027 revenue growth to beat 65%, with EPS growing even faster. There is no formal target past 2027.

    celestica ownership pie

    What are institutions doing?

    Big money is clearly involved. MarketBeat shows institutions own about 67% of the stock, and 606 institutions held shares over the past two years. They bought about 47 million shares in the last 24 months.

    Why Celestica may be worth a look

    Growth is the first reason. Revenue is up 62% and still accelerating, with guidance pointing to even faster growth in 2027.

    Quality is the second. Margins are at record highs, and the return on invested capital was 55.5% in Q2 on the company’s own measure.

    Funding is the third. Free cash flow is positive, and the $3 billion raise removes most financing worries.

    Visibility is the fourth. Ten separate 1.6T programs spread the risk across many projects instead of one.

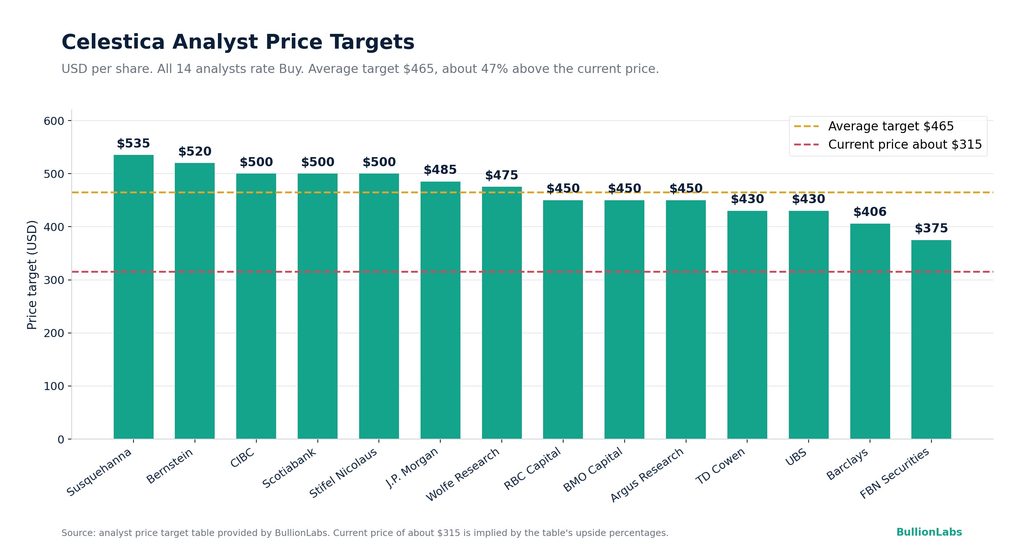
    celestica price targets

    Celestica stock price targets from Wall Street

    Wall Street is bullish on Celestica. Every analyst in my table rates it a Buy.

    The highest target is $535 from Susquehanna. The lowest is $375 from FBN Securities. The average sits near $465, about 47% above the recent price.

    Targets are opinions, not promises, so keep watching the next earnings report.

    What to watch

    Dilution is real. Component shortages could slow shipments. Customers are concentrated among a few giant cloud and AI names, so a pullback in their spending would hit hard. Leadership is also changing, with a new structure starting October 1.

    Q3 results are due soon, so the next update will test whether the guidance holds.

    Disclosure: The author holds a long position in $CLS stock at the time of writing

    Sources: Investing.com, Celestica, Tradingview, MarketBeat

  • Memory Chip Makers Are Locking In Customers for Years. Here Is What the Deals Actually Say

    Memory Chip Makers Are Locking In Customers for Years. Here Is What the Deals Actually Say

    Memory has a famous habit. Prices soar, makers build too much, prices crash, and everyone suffers. A table of memory chip long term agreements from the biggest memory makers suggests the industry is trying to break that pattern.

    memory lta agreements at a glance

    One note on the data first. Micron’s figures are as of the third quarter of calendar 2026, while the others are as of the second quarter.

    Real money is changing hands

    Micron reports US$32 billion in deposits and commitments, up from US$22 billion at the second quarter, plus about US$150 billion in remaining contract value from its signed agreements. An unnamed US NAND maker reports US$59.8 billion in remaining contract value at quarter end, rising to US$91.1 billion once contracts signed after quarter end are included. It also cites US$16.8 billion in financial guarantees, but those are mostly held by or through third party institutions, so they are not the same as cash in the bank. Samsung says it has received about a quarter of its prepayments so far, with more expected. SK hynix says deposits are part of its contracts but gives no amounts.

    Chart of remaining contract value and share of volume covered by long term agreements

    Price floors, and sometimes ceilings

    Samsung has set a minimum price floor for mainstream products, designed to reduce future investment risk. The US NAND maker uses a mix of fixed and variable pricing, where the variable part has both a floor and a ceiling, and it says gross margin stays around 80% even at trough pricing. Micron said in the second quarter that it had a guaranteed gross margin above any prior cycle peak. SK hynix describes a pricing band to cope with volatility, but says pricing will not be uniform across customers.

    The ceilings matter. Customers are getting protection too, so part of the upside is capped.

    How long, and how binding

    Micron’s agreements run through 2031, with five years for data center and consumer customers and three years for automotive. Samsung’s are five years but renegotiated annually on a rolling basis. SK hynix averages about five years, and the US NAND maker offers up to five years with a weighted average above four.

    How binding they are also differs. Micron explicitly uses take or pay with binding volume commitments. Samsung and Kioxia describe binding contract terms for both sides. SK hynix talks about long term volume commitments plus deposits. The US NAND maker sets supply commitments each year by quarter. So “locked in” means different things at different companies.

    Coverage is still partial

    In the second quarter, Micron’s agreements covered about 20% of DRAM shipments and about a third of NAND shipments. It expects about 35% of revenue to be covered by 2030, with a goal of 50%. Samsung puts coverage at 60 to 70% of capacity, with agreements finalized with its top five data center customers and five more in final stages. The US NAND maker expects about half of bit volume covered in its fiscal 2027 and two thirds in 2028, and Kioxia targets 50% of shipments by calendar 2028. The spot market still matters.

    Where the demand comes from

    Most of it is data center and AI related. SK hynix lists server DRAM, HBM and enterprise SSD, Samsung is HBM focused, and Kioxia and the US NAND maker name hyperscale and AI infrastructure customers. Micron also includes consumer and automotive.

    What the table does not tell you

    It says nothing about whether customers can afford to honor these deals if demand weakens, or how firmly each clause would hold up. It is a snapshot from company data, not a guarantee.

    My takeaway

    These agreements give memory makers more visibility and some downside protection than they had in past cycles. But the coverage is partial, the terms vary, and some of the upside is capped. I would call it a smoother ride, not the end of the cycle.

    Want more on the companies behind these agreements? Here are my earlier posts:

    And for the demand side, the AI infrastructure buildout that these contracts are meant to serve:

    Disclosure: The author holds a long position in $MU and $SKHY stock at the time of writing.

  • XNDU Stock: Xanadu Quantum Technologies Explained

    XNDU Stock: Xanadu Quantum Technologies Explained

    Xanadu Quantum Technologies Inc. (NASDAQ: XNDU)

    What does Xanadu actually do?

    XNDU stock represents Xanadu Quantum Technologies, a Toronto company founded in 2016. It builds quantum computers that run on light. Most rivals cool their chips to near absolute zero. Xanadu’s photonic chips work at room temperature and can be made in chip factories. That is the core pitch.

    It also sells software. PennyLane is its open source library for programming quantum computers and linking them to machine learning tools. Catalyst helps compile and speed up that code. Customers can also reach its X series machines through the cloud.

    The team is about 252 people. The company went public in March 2026 through a merger with a SPAC called Crane Harbor. It now trades on Nasdaq and the TSX. The deal brought in roughly $302 million, well below the $500 million first hoped for.

    What have they achieved lately?

    In the short term, the story is about proof points. Over the past year Xanadu has shown:

    • Aurora, a modular and networked photonic quantum computer.
    • Error resistant light qubits, called GKP states, made on a chip and published in Nature.
    • 12 logical GKP qubits with real time error correction.
    • A move up to Stage B of the DARPA Quantum Benchmarking Initiative, worth up to $15 million.
    • This year, ultra low loss chip packaging in June, a new quantum memory algorithm called QROM in May, and a 20 qubit fluid dynamics run with AMD that was 25 times faster than a CPU workflow.

    They are also building. The Inception facility in Toronto is 158,000 square feet, with 65,000 square feet of cleanrooms for chip packaging and module assembly.

    Where is it heading?

    The goal is a fault tolerant quantum computer. In plain words, a machine that fixes its own errors and can run long, useful programs. Management talks about a quantum data center in Canada by 2029.

    The roadmap they shared on August 31 runs like this:

    • 2026 to 2027: build the qubit factory.
    • 2028 to 2029: reach the fault tolerance threshold.
    • 2029 to 2030: launch the quantum data center, with up to 200 logical qubits in 2029.
    • 2030 to 2031 and beyond: 500 logical qubits in 2030, then more than 1,000 in 2031.

    The key number is photon loss. Light gets lost inside chips, and that is the main source of errors. The plan is to cut loss from 24.1 times above the needed threshold in 2026 down to 1.0 times by 2030. That is a big climb.

    The latest news speaks to that gap. On September 9, 2026, Xanadu and ASML announced a collaboration on advanced lithography for Xanadu’s photonic chips. ASML is a leading supplier to the semiconductor industry. The work looks at how lithography and process choices affect line edge roughness, which scatters light out of the chip and adds optical loss. Cleaner patterning could help push loss down toward the roadmap target. It is described as joint exploration, so treat it as a technical positive, not a revenue event.

    Are they on track?

    By their own scorecard, yes. The milestones they announce keep landing. DARPA moved them to Stage B, and the new roadmap is more detailed than the old one. Earlier they spoke of up to 500 logical qubits in 2029 to 2030. The new version spreads that out, with 200 in 2029 and 500 in 2030. I read that as a clearer schedule, but it is worth watching.

    The honest caveat is that nobody outside the company has verified the hard part yet. Xanadu itself says it has not built a large scale fault tolerant machine. A 24 times gap on photon loss is the real test. DARPA’s Stage B review is a year long and started in November 2025, so a decision could come around the end of this year or early next. That is my estimate, not a company date.

    Is revenue growing?

    Yes, but it is small and lumpy. Full year revenue was $2.5 million in 2023, $1.6 million in 2024 and $4.6 million in 2025. That is up about 190 percent in 2025 after a dip in 2024. Trailing twelve month revenue is $7.2 million.

    XNDU stock_revenue_annual

    Quarter by quarter in 2026:

    • Q1 revenue was $2.83 million, about four times the year before.
    • Q2 revenue was $1.51 million. That is down 46.6 percent from Q1, but up 42.5 percent from $1.06 million in Q2 2025.
    • For the first half, revenue was $4.34 million versus $1.76 million a year ago. That is up about 147 percent.
    XNDU stock_revenue_quarterly

    Most of the money comes from government work, mainly DARPA, so it moves in steps. Gross margin looks great at about 93 percent, but the base is tiny. One more thing. Analysts expect $9.21 million for 2026. After $4.34 million in the first half, the second half needs about $4.9 million. That is roughly double the Q2 pace.

    What about earnings per share?

    The EPS history is messy because of the merger. Some sites show a 2025 loss of $14.29 per share. That uses the old share count of about 4.9 million, so ignore it. On today’s share count, 2025 was a loss of about $1.07 per share.

    XNDU stock_eps loss per share

    Q2 2026 was a loss of 14 cents per share. Net loss was $42.05 million, up from $20.6 million in Q1 and $15.14 million in Q2 2025.

    Analysts see these full year losses per share:

    • 2026: 50 cents.
    • 2027: 32 cents, which is about 35 percent better.
    • 2028: 34 cents.
    • 2029: 66 cents, per one tracker.

    So EPS is not improving in a straight line. Only two to four analysts cover each year, so treat these as rough. The next report is expected around early December, with a loss of about 9 cents and revenue near $2.79 million.

    Did EBITDA and cash flow improve?

    No. Both got worse as the company spent more to build.

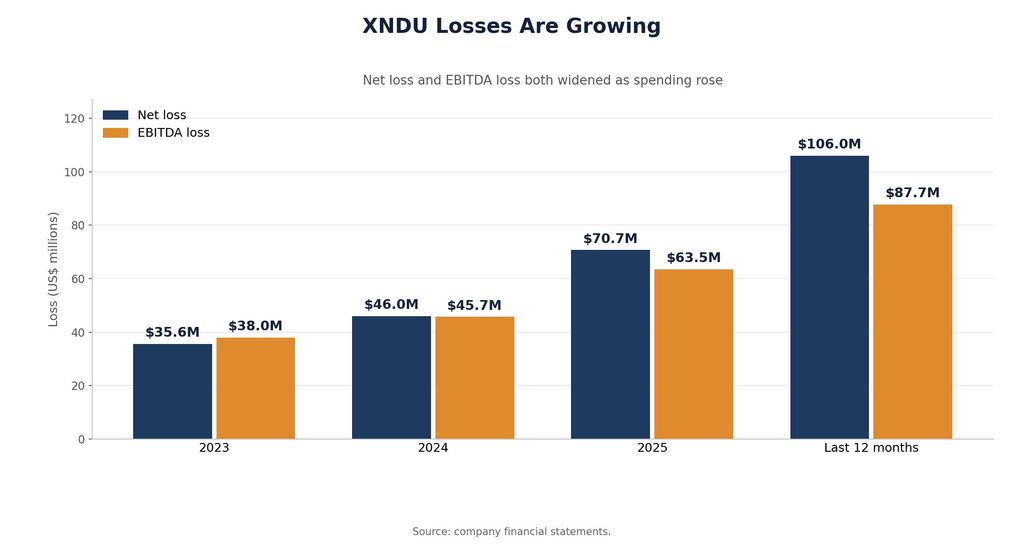
    Net loss was $35.6 million in 2023, $46.0 million in 2024, $70.7 million in 2025 and $106.0 million over the last twelve months. EBITDA losses went from $38.0 million to $45.7 million to $63.5 million, and $87.7 million over the last twelve months. Adjusted EBITDA loss was $13.9 million in Q1 and $21.3 million in Q2.

    XNDU stock_net loss and ebitda

    Where did the extra spending go? Research and development was $69.6 million over the last twelve months, up from $55.2 million in 2025. Selling and admin costs were $34.3 million, more than double the $16.6 million in 2025. Life as a public company is not cheap.

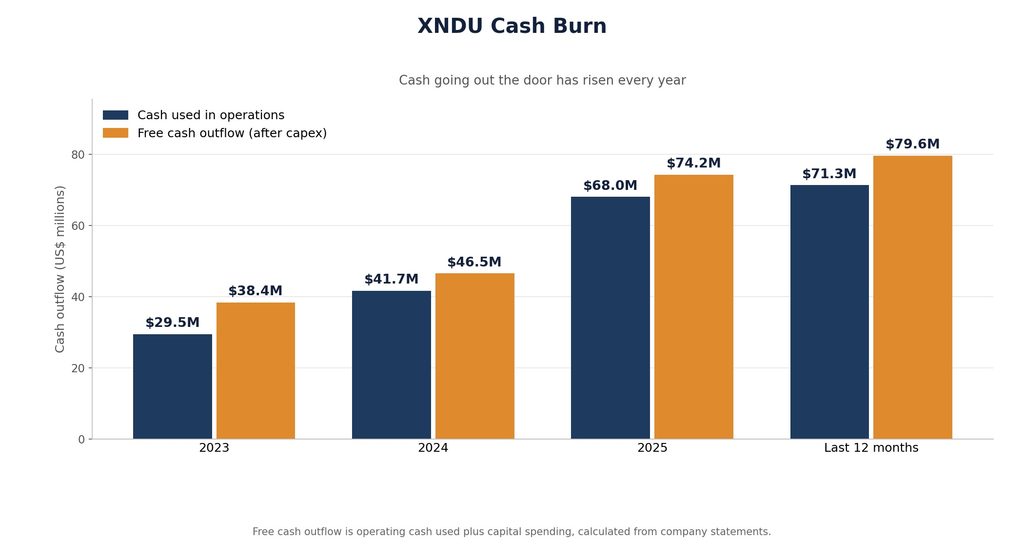
    Cash used in operations was $29.5 million in 2023, $41.7 million in 2024, $68.0 million in 2025 and $71.3 million over the last twelve months. Add capex, and free cash flow outflow rose from about $38 million to $47 million to $74 million, then $80 million. Those last figures are my own math from the statements.

    The cash balance looks great only because of financing. Cash is $312.8 million, up from $16.2 million at the end of 2025. Nearly all of that came from selling shares.

    What is the financial status?

    The balance sheet is solid for a company at this stage. Cash is $312.8 million. Total debt is $59.1 million, made up of $32.4 million of long term debt and about $26.8 million of leases. That leaves net cash of about $254 million. Equity is $313.1 million, and the old convertible preferred stock is gone. Cash is about a quarter of the market cap.

    XNDU stock_cash balance

    The company also lists about $686 million of total available capital. That counts the cash, a $140.2 million Canadian government grant (CAD $195 million) and $232.8 million still available under a share sale facility with Yorkville. The grant is money that does not dilute shareholders. The share facility does.

    How much cash does XNDU burn, and how long will it last?

    In Q2, adjusted EBITDA loss was $21.3 million and capex was $6.4 million. That is about $28 million a quarter. It lines up with the cash change too. Cash rose $40.3 million even after they raised $67.2 million from share sales, which implies a burn near $27 million.

    XNDU_cash flow

    Capex jumped from $0.3 million in Q1 to $6.4 million in Q2. Over the last twelve months it was $8.3 million. The CFO said capex should rise further in the second half as they buy tools and run more chip tapeouts. Hiring is also going up.

    Here is my rough runway math. These are my estimates, not company numbers.

    • At $28 million a quarter, cash alone lasts about 11 quarters, into early 2029.
    • If burn climbs to $45 million a quarter, cash alone lasts about 7 quarters, into early 2028.
    • At that higher burn, the full $686 million lasts about 15 quarters, into early 2030.

    Management says the capital funds them through the 2029 to 2030 milestones. That may be fair. But the share facility depends on the stock price. At $4.30, selling the remaining $232.8 million would mean about 54 million new shares. That is roughly 18 percent more shares. I would plan for more dilution and probably another raise before real revenue shows up.

    When could they turn profitable?

    Not soon. Analyst revenue estimates are $9.2 million for 2026, $11.5 million in 2027 and $16.5 million in 2028. Then comes the leap, with $65.8 million in 2029, $255 million in 2030 and $743 million in 2031. Those late numbers come from very few analysts, and the ranges are wide. EPS estimates still show losses through 2029. My read is that profit is unlikely before 2030 and more likely 2031 or later, and only if the roadmap works.

    XNDU_revenue long term estimates

    What is the guidance for XNDU stock?

    There is no formal numeric guidance. The CFO said they are not giving explicit targets yet, but the direction is clear. More engineers, more tapeouts, more capex in the second half. He also said more detailed spending guidance would come later.

    On the technology side, the long term guidance is the roadmap above. Fault tolerance in 2028 to 2029, a data center by 2029 to 2030, and 1,000 plus logical qubits in 2031.

    XNDU_analyst price targets

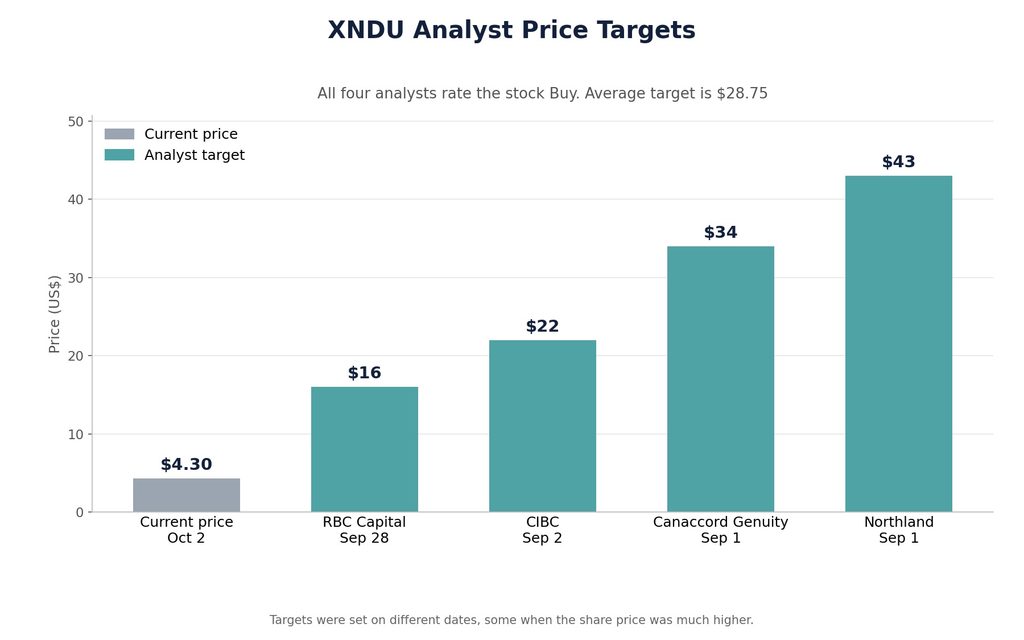
    Wall Street is upbeat on XNDU stock. Recent price targets are $16 from RBC Capital, $22 from CIBC, $34 from Canaccord Genuity and $43 from Northland. All four say Buy. Remember that the stock has fallen a lot since some of these were set.

    Who owns XNDU stock?

    Here is what we can see now. One data source shows institutions holding 34.03 percent, or 103.57 million shares. Insiders hold 17.31 percent, private equity and venture firms 24.73 percent, and the public 23.94 percent. Other trackers give different splits, with institutions anywhere from about 8 percent to 31 percent, depending on how they count. Treat the exact number loosely.

    XNDU_ownership pie
    XNDU_top shareholders

    The direction is up. One tracker counted 22 institutional holders as of Q1 2026. Another showed about 41 by early July, with funds adding. Founder and CEO Christian Weedbrook is the largest holder at about 15.6 percent, which is a good sign for alignment.

    The big risk here is supply. Earlier this year Xanadu registered about 293.6 million shares for resale by early holders. The stock fell roughly 68 percent in a day on the news. Those shares can still weigh on the price.

    Is XNDU stock worth investing in?

    The bull case is simple. If photonic quantum computing works at scale, Xanadu is one of the few public pure plays, which is the core appeal of XNDU stock. The stock has already reset hard. Cash is about a quarter of the market cap. And the roadmap has real checkpoints to measure.

    The bear case is just as clear. At $4.30 and 2026 revenue of about $9 million, the stock trades near 140 times forward sales. Losses are growing. Revenue is lumpy. The technology still has a big gap to close. More dilution is likely. And rivals such as IBM, Google and PsiQuantum are well funded.

    Other quantum stocks take different routes. For comparison, read the deep dives on IonQ and trapped ion quantum computing platforms and Quantinuum and integrated quantum hardware with cybersecurity software.

    This is a venture style bet in a public stock. Size it that way.

    What is the moat?

    I see five layers, with different strengths.

    • The approach. Light based chips run at room temperature and can use chip factories. That could make scaling cheaper, if the loss problem is solved.
    • PennyLane. About 30.8 percent of surveyed developers used it, second only to IBM’s Qiskit. It sees about 1.1 million installs a month and over 1,890 public code projects depend on it. Users and partners include Lockheed Martin, Rolls Royce, Toyota, Volkswagen, AMD and Mitsubishi Chemical.
    • Government backing. DARPA Stage B, a CAD $195 million grant and a spot in Canada’s Quantum Champions Program.
    • Manufacturing. The Inception facility and tool partners such as ASMPT, Bluefors, DISCO, EVG, FiconTEC and MPI. In September 2026 it also teamed up with ASML on lithography.
    • Talent and leadership. A founder led team with deep research roots.

    The weak spot is that PennyLane is open source and works with other hardware too. It builds mindshare, but turning that into revenue is not proven yet. The hardware moat only becomes real if they deliver on the roadmap.

    What I would watch next

    • The DARPA Stage B outcome.
    • Proof that photon loss is falling toward the target, including any results from the ASML lithography work.
    • The detailed spending guidance management promised.
    • The Q3 report in early December, and whether revenue gets close to the $2.8 million estimate.
    • How much of the share facility they use, and at what price.
    • Selling pressure from the resale shares.

    Bottom line. XNDU stock comes with real technology, real backing and a decent cash pile. It also has rising losses, no profit in sight for years, and a stock that still swings hard. If you are drawn to it, know why you own it and how much you can afford to lose.

    More quantum stock deep dives

    Sources: Tipranks, SeekingAlpha, Tradingview, Xanadu

    Disclosure: The author holds a long position in $XNDU stock at the time of writing

  • NBIS Stock Analysis: Is Nebius Worth Buying in 2026?

    NBIS Stock Analysis: Is Nebius Worth Buying in 2026?

    Nebius Group N.V. (NASDAQ: NBIS)

    NBIS stock is up about 180% this year. Revenue is exploding, but so are costs and debt.

    What does Nebius do?

    Nebius is an AI cloud company. It rents out GPU computing power. It is building a full platform for developers and companies, from data and model training to live deployment.

    The AI cloud business makes up about 98% of group revenue. Nebius also owns Avride, an autonomous vehicle platform, and TripleTen, an edtech service. Both are small. Nebius competes in a crowded field of AI cloud and GPU providers, so we also track $IREN.

    Short term technology progress

    Nebius is scaling power and products at the same time.

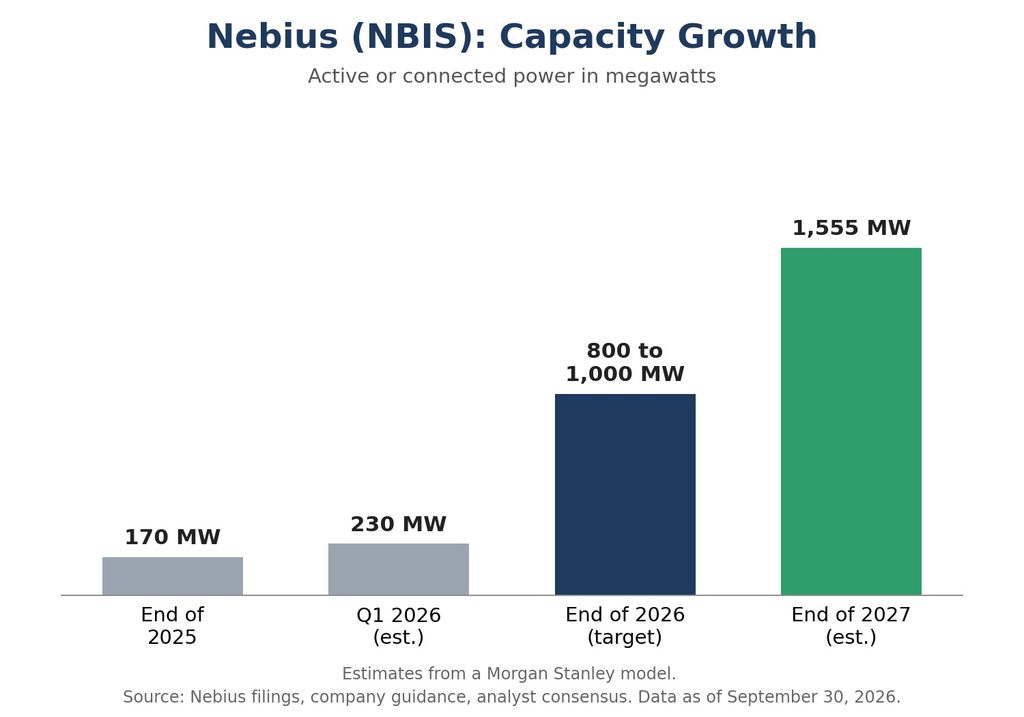
    It ended 2025 with about 170MW of active power, against a target of 100MW. It now targets 800MW to 1GW of connected power by the end of 2026.

    nbis capacity growth

    On the product side, it runs Token Factory, an inference platform with open models such as Kimi K3, GLM 5.2 and Nemotron Ultra. It also plans to use Nvidia’s Groq 3 LPX for fast inference. In September, Palantir named Nebius its preferred sovereign AI infrastructure partner.

    Long term technology progress and goal

    The next big step is Nvidia’s Vera Rubin chip. Meta signed a five year deal worth up to $27 billion, with $12 billion tied to large Vera Rubin deployments from 2027.

    Nebius also plans a Pennsylvania site. The first 250 to 300 megawatts go live by the end of 2027. The site reaches 1.2 gigawatts by 2030. Contracted power is now guided to 5GW by year end, raised from more than 4GW.

    The goal is simple. Nebius wants to be a full AI hyperscaler that competes with AWS, Azure and Google Cloud.

    Is Nebius on track with its roadmap?

    So far, yes. In 2025, ARR ended at $1.25 billion, ahead of the $900 million to $1.1 billion guidance. In Q2, management reaffirmed all 2026 guidance.

    The hard part is still ahead. ARR must rise from $3.0 billion to $7 billion to $9 billion by December. Most of this year’s capacity comes online in the second half. One Morgan Stanley model has active power near 230MW in Q1 and 780MW by Q4. That is a steep climb.

    Is revenue growing?

    Yes, very fast.

    Q1 revenue was $399.0 million, up 684% from a year earlier. Q2 revenue was $582.3 million, up 454% year over year and 46% from Q1. Annualized run rate revenue hit $3.0 billion in June, up 56% from $1.9 billion in March.

    nbis revenue growth

    Full year 2025 revenue was $529.8 million. Analysts expect $904 million in Q3, which is about 55% growth over Q2 by my math. Nebius reports around October 22.

    How is EPS trending?

    EPS is still negative, but the trend is mixed.

    Reported EPS was a loss of $0.95 in 2024 and a loss of $1.83 in 2025. In Q2, GAAP EPS was a loss of $0.68, while adjusted EPS was a loss of $0.12.

    nbis eps progress

    Do not trust the Q1 headline profit. Net income was $621.2 million, but the adjusted net loss was $100.3 million. In Q2, the adjusted net loss narrowed to $33.2 million, while the GAAP net loss was $190.4 million.

    Analysts expect losses per share of $2.23 in 2026, $3.49 in 2027 and $1.44 in 2028, most likely because depreciation rises with the GPU buildout. The first profit, $10.49 per share, comes in 2029. Only two analysts cover that year, so treat it as a rough guide.

    Did EBITDA improve?

    Yes, a lot. Adjusted EBITDA went from a loss of $21.0 million in Q2 2025 to a gain of $236.2 million in Q2 2026. The margin rose from 32% in Q1 to 41% in Q2.

    Gross margin is a healthy 74% over the last twelve months. But EBIT margin is still negative 37% because GPUs lose value fast.

    How is cash flow?

    Operating cash flow improved sharply. It was positive $2.26 billion in Q1, versus an outflow of $184.1 million a year earlier. Q2 added another $2.3 billion.

    There is a catch. Much of that cash comes from customer prepayments. Deferred revenue rose from $1.58 billion to $5.98 billion in the first half. Free cash flow is still negative. In Q2, $2.3 billion of operating cash minus $5.7 billion of capex leaves a gap of about $3.4 billion.

    How much is Nebius spending on capex?

    Q1 capex was $2.47 billion. Q2 jumped to about $5.7 billion. The 2026 guide is $20 billion to $25 billion.

    nbis capex

    That leaves roughly $12 billion to $17 billion for the second half. That is about $6 billion to $8 billion per quarter by my math.

    How much funding does Nebius need, and how long does cash last?

    Cash fell from $9.3 billion in March to $8 billion in June.

    Management plans to fund growth in layers. It expects more than $9 billion in customer prepayments in 2026. In July it raised $775 million in secured debt at SOFR plus 2.50%, backed by more than $40 billion in customer commitments. It also has an at the market stock program and may issue corporate debt. Earlier this year it raised $4.3 billion in convertible notes and $2 billion in prefunded warrants. One analyst put debt near $8.5 billion.

    My rough math: $8 billion in cash, plus $0.8 billion of new debt, plus about $4 billion to $5 billion of prepayments still to come, totals about $13 billion. That is near the low end of second half capex. So 2026 looks mostly funded, with a possible gap of a few billion dollars. 2027 will need more capital. Expect more debt and more share dilution. This is an estimate, not company guidance.

    When could Nebius become profitable?

    It is already EBITDA positive. Net profit looks about three years away, based on analyst estimates for 2029. Consensus revenue climbs from $3.34 billion in 2026 to $12.3 billion in 2027, $23 billion in 2028 and $36.6 billion in 2029.

    What is the guidance?

    For 2026, Nebius guides to group revenue of $3 billion to $3.4 billion, ARR of $7 billion to $9 billion, an adjusted EBITDA margin near 40% and capex of $20 billion to $25 billion. That implies about $2.0 billion to $2.4 billion of revenue in the second half.

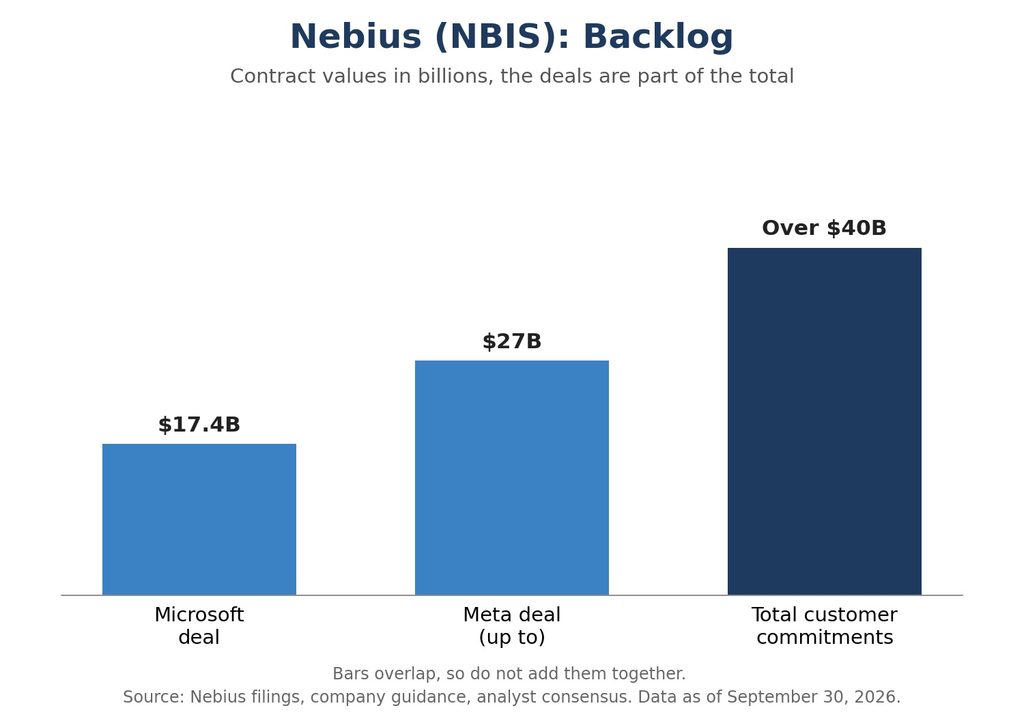
    nbis backlog

    Long term, there is no formal 2027 guide yet. Management says formal guidance comes later this year. The long term story rests on the $40 billion backlog, the Meta and Microsoft contracts and the 5GW power target.

    Are institutions buying NBIS?

    I cannot give a clean three year percentage. Nebius was called Yandex N.V. until August 2024, so older data is not comparable.

    Data providers also disagree. MarketBeat showed 21.9% in October 2025. Fintel shows about 54%. Financhill shows about 66%.

    nbis ownership white

    The direction is clearly up. Institutional holders rose from 283 to 307 last quarter, and shares held rose 27%. Lone Pine and Soros opened new positions in Q2. Situational Awareness LP disclosed a 5.6% stake. Orbis cut its stake sharply.

    What do analysts say?

    Most say buy. Most price targets run from $250 to $410. BTG Pactual is neutral at $223. Northland is at $410, BNP Paribas at $399, Truist at $355, Goldman Sachs at $328 and Citi at $324. D.A. Davidson rates it hold at $250.

    nbis price targets

    The bear case is loud too. Rothschild Redburn started with a Sell and an $84 target. It cites falling GPU rental prices, hyperscalers building their own capacity and costly financing.

    Why NBIS stock may be worth it

    The case for buying is simple.

    1. Demand beats supply. Nebius said it sold out its capacity again in Q1.
    2. It has pricing power. It plans roughly 20% GPU price hikes from October 1.
    3. It has big, named customers and a backlog above $40 billion.
    4. Margins are improving fast.
    5. Nvidia invested $2 billion, which helps with chip access.

    The risks to weigh

    Capex is huge. Debt is rising. Dilution is likely. GPU prices could fall. The stock is up a lot, and a few big customers drive much of the demand. A miss on the second half ramp could hit the price hard.

    NBIS stock fits investors who accept high risk for high growth. Keep position size modest. Watch Q3 results on October 22 and the 2027 guidance.

    Sources: Tipranks, SeekingAlpha, Tradingview, TIKR

    Disclosure: The author holds a long position in $NBIS stock at the time of writing

  • Micron Technology: Wall Street Keeps Raising the Bar

    Micron Technology: Wall Street Keeps Raising the Bar

    Micron Technology (NASDAQ: MU)

    Micron closed at $977.50 on September 17, 2026. That’s up 5.5% on the day. In fact, the stock has been on a wild run this year, and the analyst notes keep piling up in its favor.

    Analysts Are Overwhelmingly Bullish

    Since the last earnings report on June 24th, most major firms have either reiterated or raised their price targets on $MU. Out of the 27 ratings tracked here, only Goldman Sachs is sitting on a Hold. Meanwhile, everyone else has a Buy.

    mu price targets

    The targets are spread pretty wide. For instance, Melius Research is the most bullish at $2,200. Similarly, Cantor Fitzgerald, Barclays, and Susquehanna are all sitting at $2,000. A lot of firms bumped their numbers up fast over the summer. As an example, Barclays went from $1,175 to $2,000. Likewise, Phillip Securities jumped from $530 all the way to $1,870. Even Melius itself moved from $1,100 to $2,200 in just a few months.

    The Real Story Is Memory

    The bigger story behind all this is memory. To begin with, Nvidia confirmed it’s raising AI server prices by more than 15%, and the reason is simple. Server DRAM roughly doubled in price during Q1 2026. In addition, some reports show an 80 to 90% jump across DRAM, NAND, and HBM in that same stretch.

    Micron sits right in the middle of this. Along with Samsung and SK Hynix, it’s one of only three companies that actually make the high bandwidth memory these AI chips need. As a result, that gives it real pricing power. Furthermore, analysts expect this shortage to stick around too. Gartner sees it lasting into 2027, while Deloitte thinks AI server DRAM prices could roughly quadruple this year.

    Demand Keeps Outpacing Supply

    There’s a demand side to this too. For example, Nebius, an AI cloud provider, has been benefiting from rising GPU rental rates, with H100 pricing up about 20% year to date. Overall, it’s another sign that compute demand is outpacing supply across the board, which only adds more pressure on the memory side where Micron plays.

    The Takeaway

    Put it all together and the setup looks straightforward. Heavy AI demand is pushing up GPU and server prices. Consequently, that’s tightening memory supply. Ultimately, that’s putting Micron in a strong position heading into the rest of the year.

    Source: Tipranks

    Disclosure: The author holds a long position in $MU stock at the time of writing

  • Zinc Batteries: Solving US Long-Duration Power

    Zinc Batteries: Solving US Long-Duration Power

    Eos Energy Enterprises, Inc. (NASDAQ: EOSE)

    Every few years, a new company promises to fix the battery problem that lithium ion cannot solve. Most fade. Eos Energy Enterprises (NASDAQ: EOSE) is different. It has gotten products into the ground. It has built a factory. It has started signing serious contracts. And it is doing all of this on a chemistry almost nobody else is scaling: zinc.

    This piece covers what the company does, why AI data center developers are suddenly paying attention, and where the business stands today. It draws on the company’s own filings and recent reporting, not investor hype.

    What Eos Energy Actually Does

    Eos was founded in 2008. The company is now headquartered in Pennsylvania, after relocating from Edison, New Jersey. Eos designs, manufactures, and sells long duration battery energy storage systems, usually shortened to BESS. In plain terms, these are large batteries. Utilities, industrial sites, and commercial customers use them to store electricity and release it over several hours, rather than seconds or minutes.

    The Znyth Chemistry

    A zinc based aqueous battery, called Znyth, sits at the core of the technology. It powers the company’s newest battery module, the Z3. Znyth uses just five commodity materials. None of them are rare earth or conflict minerals, and that sets it apart from lithium, cobalt, and other materials that are often imported and geopolitically sensitive.

    zinc

    The process is simple to describe. During charging, zinc deposits onto the battery’s electrodes. During discharge, it dissolves back into the electrolyte. Engineers have understood this electrochemical idea for decades. Eos spent years turning it into something that can be manufactured at volume and sold at a competitive price.

    The Product Line

    The finished systems carry names like the Eos Cube, Hangar, and Indensity. Eos builds them for 3 to 16 plus hour discharge windows. The industry generally calls this long duration or mid duration storage.

    What Makes the Technology Different

    Lithium ion dominates the battery storage market today. Tesla, Fluence, CATL, and Sungrow control the large majority of installed capacity worldwide. Lithium performs well at short bursts, typically two to four hours. But it hits real limits past that window. Cost per stored megawatt hour climbs. Fire risk becomes a bigger operational concern at scale. And the supply chain runs mostly through overseas mining and processing.

    Eos pitches zinc as a direct answer to those pain points. A few things stand out.

    Safety and Durability

    The system is non flammable. Its aqueous, water based chemistry avoids the thermal runaway risk that defines lithium ion. That means the Z3 skips the costly fire suppression and active cooling equipment that lithium installations typically require.

    The battery also holds up over time. Eos rates its cells for roughly 6,000 charge and discharge cycles, which works out to about 20 to 25 years of service. The company says the batteries deliver full depth of discharge with very little capacity fade as the years go on.

    Domestic Sourcing and Incentives

    Eos builds and sources the batteries entirely in the United States. That qualifies them for domestic content rules and for federal incentives, including the Section 45X production credit and the Section 48E investment tax credit under the Inflation Reduction Act. Together, these credits are worth an estimated 90 million dollars or more per 2 GWh production line each year.

    The systems are also simpler to run day to day. They need no active thermal management, they tolerate a wide operating temperature range, and they carry lower ongoing maintenance overhead than a lithium fleet of similar size.

    None of this makes zinc a universal replacement. Lithium still wins on very short, high power bursts. Eos is chasing the multi hour middle ground instead, roughly 4 to 16 plus hours of discharge. That happens to be exactly what grid operators, utilities, and increasingly data centers are short on.

    The AI and Data Center Angle

    AI data centers pull enormous, sustained amounts of power. The U.S. Energy Information Administration expects power demand to hit record highs in both 2026 and 2027, largely because of AI driven load growth. Global data center electricity demand could roughly triple by 2030.

    The real challenge for hyperscalers is not simply finding more electricity. It is finding firm, reliable, long duration capacity fast, often faster than the traditional grid interconnection process can deliver. That challenge lines up naturally with what Eos already builds. AI workloads need power for longer stretches than lithium’s two to four hour profile comfortably covers, and they need it now rather than in five years.

    How Eos Is Capturing This Demand

    Eos has gone after AI power demand in two main ways.

    First, data center customers now make up roughly a fifth of the company’s total commercial pipeline. That segment barely existed for Eos two years ago.

    Second, in April 2026, Eos signed a joint development agreement with TURBINE-X Energy. The partnership builds behind the meter private power infrastructure for AI data centers, pairing gas fired generation with Eos’s Indensity battery architecture. The goal is firm, dispatchable, on site power delivered in months rather than years. TURBINE-X is targeting up to 2 GWh of Eos battery storage across a 36 month rollout, with initial deployments expected in 2027. Eos CEO Joe Mastrangelo has called AI data center demand an accelerant for the company’s business.

    This positions Eos alongside much bigger players serving hyperscale data centers, names like NextEra Energy Resources and Fluence Energy. That is a real jump in visibility for a company that, until fairly recently, was mostly known as a struggling grid storage upstart.

    Production and Manufacturing

    Eos manufactures in Pennsylvania, mainly at its Thorn Hill facility in Marshall Township, near Pittsburgh. The company commissioned a second battery production line there in mid 2026, and it already runs faster cycle times and higher yields than the first line. Eos is consolidating manufacturing into Thorn Hill specifically to cut conversion costs. The facility is targeting roughly 4 GWh of annual production capacity by the end of 2026.

    A separate U.S. Department of Energy Loan Programs Office loan guarantee, worth up to roughly 305 million dollars, is financing two additional manufacturing lines for next generation zinc bromine systems. Eos could add two more lines on top of that, for four in total, across Turtle Creek and Duquesne, Pennsylvania. The DOE says this build out could reach over 8 GWh of annual storage capacity by 2026, enough to instantaneously power more than 300,000 average U.S. homes.

    Costs are moving in the right direction too. Eos reported a 12.5 percent material cost reduction on the Z3 product. It achieved that reduction in under a year through supplier renegotiation and simpler design choices.

    Backlog, Pipeline, and Financials

    Looking at the most recent reporting from Q2 2026, a few numbers stand out.

    Backlog and Pipeline

    Backlog sits at approximately 807 million dollars. That figure is up 25 percent from the prior quarter and 20 percent year over year, representing 3.4 GWh of contracted storage capacity. It is a company record.

    backlog

    The commercial opportunity pipeline tells a similar story. It includes proposals and letters of intent rather than signed contracts, and it has grown to approximately 24.6 billion dollars. That is up 31 percent year over year, spanning roughly 112 GWh across utility, industrial, commercial, and data center customers.

    opportunity pipeline

    Think of the pipeline as a measure of demand in the room. The backlog is the portion of that demand actually locked into paper. The chart below shows how the pipeline has grown over the past year.

    Revenue and Guidance

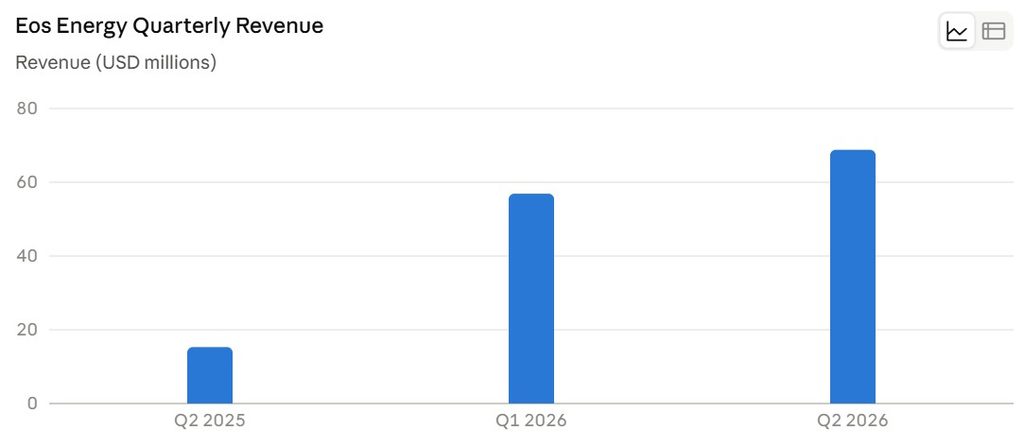
    Revenue reached 68.8 million dollars in Q2 2026 alone, up 351 percent year over year. First half 2026 revenue of 125.7 million dollars already surpassed everything the company brought in during all of 2025. Full year 2026 guidance was tightened to a range of 300 to 350 million dollars, down from a prior 300 to 400 million dollar range. Eos attributes the change mainly to its planned manufacturing consolidation into Thorn Hill.

    quarterly revenue

    Cash, Losses, and Frontier Power USA

    Cash on hand stood at approximately 364 million dollars as of June 30, 2026, including restricted cash. Profitability, though, remains a real problem. Q2 2026 gross margin came in around negative 71 percent. The net loss for the quarter reached 275.7 million dollars, driven mostly by fair value accounting adjustments, and the adjusted EBITDA loss came in at 71.4 million dollars. Eos is scaling its top line quickly while still burning a lot of cash to get there.

    One structural piece worth understanding is Frontier Power USA, often shortened to FPUSA. Eos formed this joint venture with Cerberus Capital Management and Hudson Bay Capital Management. FPUSA raised 263 million dollars to support an estimated 1 billion dollars in project deployment capital. It acts as a financing arm that turns Eos’s project pipeline into built, operating assets faster than Eos could fund on its own. FPUSA has already converted its first purchase order, the Redbird project in Texas, against a 2 GWh capacity reservation agreement it holds with Eos.

    Well Known Customers and Contracts

    The customer base spans utilities, renewable developers, and, more recently, data center infrastructure players.

    Bridgelink Investments, also known as Bridgelink Commodities, is a large renewable developer with more than 8 GW of projects in development. It holds a 1 GWh master supply agreement with Eos tied to grid resilience and energy curtailment recapture in the ERCOT market in Texas.

    Frontier Power USA is the co funded joint venture described above. It holds a 2 GWh firm capacity reservation agreement plus a broader 12 to 16 GWh development pipeline across ERCOT, PJM, CAISO, and MISO.

    Duke Energy was an early pilot customer, going back to a 1 MW, 4 MWh installation in 2019. It later became a booked order customer as well. Ameresco, Blue Ridge Power, Pine Gate Renewables, and Center Line Electric placed booked orders during the company’s earlier growth phase. TURBINE-X Energy is the joint development partner for AI data center power infrastructure. And Verdant Microgrid was an early microgrid deployment partner in California, back when the whole platform was much smaller.

    The Road Ahead

    Eos sits at an inflection point. On the surface, this looks like a boring hardware business. Underneath, there is real backlog growth, a large and diversifying demand pipeline, a factory that is actually scaling, and a policy backdrop that currently favors domestic, non lithium chemistries. Independent analysts have floated a wide range of outcomes here, from a modest re rating if the company simply keeps executing, to a meaningfully higher valuation if pipeline conversion speeds up and margins finally turn positive.

    The risks are just as real, and worth stating plainly. Eos is still losing significant money on every dollar of revenue. It remains reliant on capital markets to fund its growth. It has faced a securities fraud lawsuit tied to past manufacturing execution problems. And it depends on a fairly small number of large customers and financing partners, FPUSA among them, for near term revenue. Scaling automated battery manufacturing lines is genuinely difficult work, and Eos has stumbled on execution before.

    Still, the bigger trend behind all of this is not going away anytime soon. AI driven power demand keeps climbing. The grid badly needs longer duration storage. U.S. industrial policy keeps pushing toward domestic battery manufacturing. Whether Eos ends up capturing that opportunity at real scale, or just one of several companies competing for a slice of it, probably depends less on the chemistry itself. The chemistry does appear to genuinely work. It depends more on whether the team can keep turning its growing pipeline into profitable, delivered projects.

    Source: Eos Energy

    Disclosure: The author holds a long position in $EOSE stock at the time of writing

  • SK Hynix Is Sold Out. Robots May Be Next.

    SK Hynix Is Sold Out. Robots May Be Next.

    SK Hynix Inc. – ADR (NASDAQ: SKHY)

    The world’s top AI memory supplier is riding an unprecedented upcycle and already eyeing what comes after data centers.

    SK Hynix has spent the better part of three decades as a cyclical also ran to Samsung a memory maker whose fortunes rose and fell with the brutal boom bust rhythm of the DRAM market. That reputation no longer fits. Since Nvidia’s GPUs began shipping with SK Hynix’s high-bandwidth memory (HBM) stacked directly alongside the compute die, the company has become one of the more consequential suppliers in the entire AI hardware stack not a chipmaker riding the AI boom so much as one of the physical constraints on how fast that boom can grow.

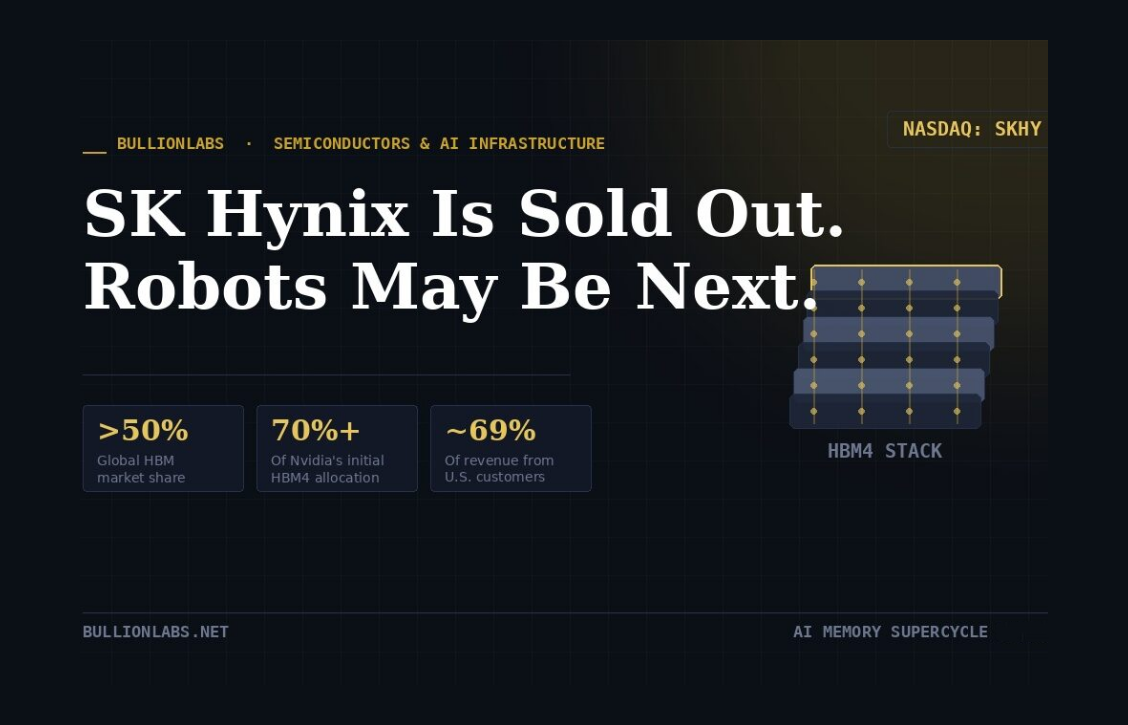
    The company controls a majority of the global HBM market and, by most industry counts, supplies more than 70% of Nvidia’s initial orders for HBM4, the next-generation standard now ramping toward volume production. Samsung is chasing hard, and Micron has carved out a smaller but growing share of the same market but for the moment, SK Hynix is setting the pace.

    From training runs to permanent memory

    For the first few years of the generative-AI boom, the bottleneck was compute raw GPU throughput for training ever larger models. That story is shifting. As AI systems move from pure training toward persistent inference, agents, and retrieval heavy workloads, the industry increasingly needs somewhere to keep data close to the processor, not just crunch it once and discard it. Every additional data center built to serve that shift needs more memory, not just more compute, and the major chipmakers Nvidia, AMD, Micron, Samsung, and SK Hynix among them have been consistent on one point: the memory shortage now underway is a structural feature of this cycle, not a temporary supply hiccup, and it’s expected to persist for the next several years.

    That raises the obvious question hanging over every AI infrastructure stock: what happens when the current wave of data center construction matures and spending normalizes? SK Hynix’s own answer, echoed by much of the industry, is that data centers are only the first leg. The next is physical a coming wave of AI-enabled robotics that would extend memory and compute demand well beyond racks in a warehouse and into cars, factories, and eventually homes. Whether that materializes on the timeline bulls expect is very much an open question, but it’s the thesis increasingly used to justify capital spending plans that would have looked reckless in any previous memory cycle.

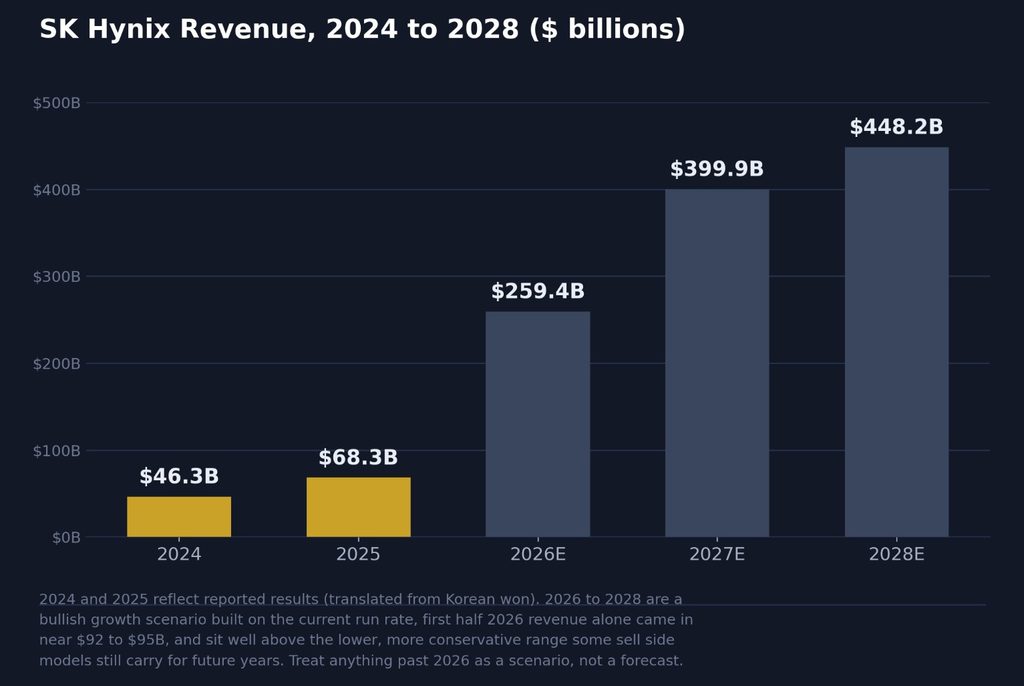
    revenue

    Beyond HBM: the next memory tier

    SK Hynix’s HBM lead is well established. Less understood is what the company is building next. Alongside SanDisk, it has been co-developing a technology called High-Bandwidth Flash, or HBF and it’s worth being precise about what that actually is, because it’s often described loosely. HBF does not stack HBM chips on top of each other. It stacks layers of NAND flash memory using the same through silicon via packaging techniques HBM pioneered, creating a new tier that sits between fast but limited HBM and large but slow SSD storage.

    The point of HBF is capacity, not raw speed: a single stack can hold many times more data than HBM at a fraction of the cost, which matters enormously for AI inference, where a model’s cached context can balloon into the hundreds of gigabytes. SK Hynix and SanDisk released the first open HBF specification in mid-2026 under the Open Compute Project, with Google and AI-chip startup Tenstorrent joining the effort a sign hyperscalers see real value in a cheaper, denser memory tier for inference workloads. Samsung appears to be pursuing a related but distinct approach of its own, stacking memory differently rather than adopting the HBF standard outright, while Micron has not yet detailed a competing product in this specific category.

    “The HBM era is ending the HBF era is coming,” one SK Hynix executive told an industry conference in late 2025, previewing what the company hopes becomes the next multi-year growth leg once HBM itself matures.

    Who’s actually buying this

    Geographically, SK Hynix’s customer base is heavily concentrated a fact that cuts both ways. The United States, driven almost entirely by hyperscaler and AI-accelerator demand, accounts for roughly two-thirds to seventy percent of total revenue depending on the quarter, with China a distant but resurgent second on the back of mobile and NAND demand. That concentration means SK Hynix’s results are unusually sensitive to a handful of customers Nvidia chief among them, alongside at least one large, unnamed hyperscaler that has separately grown into a top-tier customer in its own right and to any shift in U.S.–China trade policy or export controls.
    share of revenue by region

    What management is promising

    SK Hynix’s own guidance has become the thing to watch each quarter, if only because the company keeps having to raise it. Capital expenditure for 2026 has been pushed up repeatedly through the year into the low to mid $30 billion range by the most recent count, with some estimates, once packaging and infrastructure commitments are included, pushing past $35 billion. That’s a record for the company and among the largest capex programs in the memory industry’s history.

    • HBM and technology leadership: Management continues to guide to more than 50% global HBM share, with over 70% of Nvidia’s initial HBM4 allocation locked in.
    • Shipments and migration: Double digit sequential DRAM bit growth guided for the second half of 2026, alongside a push to get 321 layer NAND to roughly half of total NAND capacity by year end.
    • Fab scaling: Plans to expand 1c nanometer DRAM output toward 170,000–200,000 wafers per month by early 2027, and a new advanced packaging facility under construction in West Lafayette, Indiana, at a cost north of $4 billion.
    • Contract backlog: Multi year supply agreements now in place with roughly ten major hyperscale customers reportedly including Nvidia, AWS, and Google several of which include upfront cash deposits that lock in pricing years in advance.
    operating margin vs net margin

    What the market is paying for it

    Wall Street’s enthusiasm shows up most clearly in earnings-per-share growth, which the sell side expects to keep compounding even as the revenue base gets much larger. On a per common share basis (SK Hynix’s Nasdaq listed ADRs represent one-tenth of a common share, so divide by ten for the per ADR equivalent), consensus estimates have EPS climbing sharply through 2026 before growth normalizes into 2027 and 2028.

    eps growth

    Target prices: three ways of looking at the same stock

    Because so much of the bull case rests on how long the current pricing power lasts, target-price models for SK Hynix tend to spread out unusually wide. A simple earnings multiple framework 2026 consensus EPS multiplied by a range of forward P/E multiples illustrates just how much the multiple assumption matters more than the earnings number itself:

    2026 target price calculations

    The bear case assumes the market eventually re-applies the discount it has historically given Korean memory stocks and cyclical semiconductor names generally. The bull case assumes SK Hynix keeps re-rating toward the multiples U.S. peers like Micron have commanded during past AI-driven upcycles. Roll the same framework forward to 2027 EPS and the spread is similar in shape, just shifted higher anywhere from roughly $147 in a trough-multiple scenario to $237 if SK Hynix holds its 2026 multiple into the following year.

    wall street target price

    Every analyst currently covering SK Hynix’s Nasdaq ADR rates it a buy, with targets clustered between $200 and $320 a genuinely unusual amount of one directional consensus for a memory stock, and arguably a risk in itself. When an entire sell side community agrees this strongly, the disagreement that matters has usually moved into how far and how long the cycle runs, not whether the stock is a buy today.

    Who owns it

    Ownership is one area where the original draft’s figures didn’t hold up well against SK Hynix’s own disclosures, so it’s worth restating cleanly. SK Square the SK Group holding entity spun out of SK Telecom in 2021 remains the controlling shareholder with roughly 20% of shares outstanding. South Korea’s National Pension Service holds around 7–8%, and foreign institutional investors collectively led by BlackRock, Vanguard, and Singapore’s GIC own more than half the company, on the order of 54–56%. The remainder is split between domestic institutions and retail shareholders. Insider and employee ownership, by contrast, is minimal, consistent with a company of this scale.

    Sources: TradingView, TipRanks, Seeking Alpha, TIKR

    Disclosure: The author holds a long position in $SKHY stock at the time of writing