In the Rocket Lab vs SpaceX debate, the fundamentals underneath RKLB are getting stronger in ways that are easy to miss. Rocket Lab builds much of what it flies, and that structure matters more as Neutron, its medium and large rocket, moves toward flight. Below I cover three things: how Rocket Lab keeps costs down, why its all in one package is different from other space companies, and where it sits in the market against SpaceX (SPCX).
Why Rocket Lab vs SpaceX Is Closer Than It Looks
Most space companies do one or two things well. Rocket Lab makes its own rockets, spacecraft and components. When a company controls its own manufacturing, it does not stack supplier margins on top of its costs, and it can improve a design and fix a problem without waiting on a vendor. That control came largely from acquisitions like SolAero, GEOST and Mynaric, which I broke down in my Rocket Lab acquisitions timeline.
You can see this in the economic profile. Raymond James research estimates 2028 capex as a share of revenue at 6.6% for RKLB, compared with 92.5% for SpaceX and 66.0% for ASTS. Rocket Lab is projected to reach a 2028E EBITDA margin of 30.0% while spending far less of each revenue dollar on capital.
Neutron Launch Costs Fall as Cadence Scales
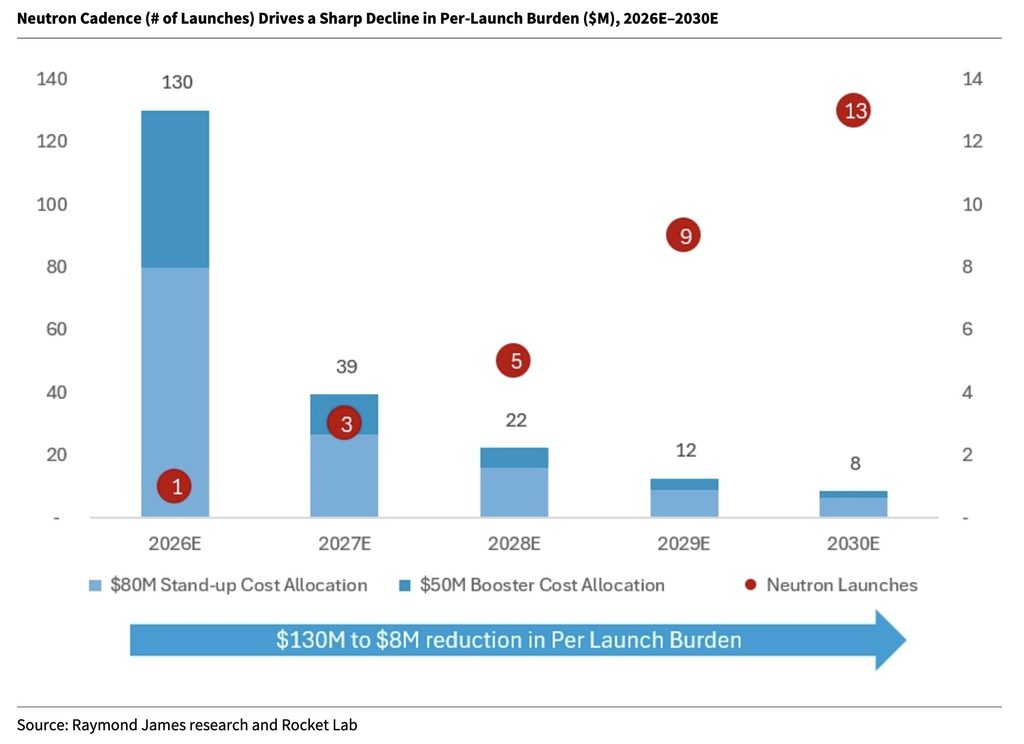
The clearest picture of the cost story is the Neutron chart from Raymond James and Rocket Lab. It splits the cost burden into two parts: an $80M stand up cost allocation and a $50M booster cost allocation. With one launch in 2026E, that burden is $130M per launch. As launches scale, the same fixed costs are spread across more flights:
2026E: 1 launch, $130M per launch
2027E: 3 launches, $39M per launch
2028E: 5 launches, $22M per launch
2029E: 9 launches, $12M per launch
2030E: 13 launches, $8M per launch
That is the move from $130M to $8M per launch. Some investors argue that at roughly $50M per launch, Neutron could become a highly profitable alternative to SpaceX for defense and commercial constellations. These are projections, not results, but the logic is simple: fixed costs shrink per launch as cadence grows.
The All in One Package Across the Space Value Chain
The Raymond James comparison rates ten companies on launch, spacecraft manufacturing, merchant components, payloads, constellations, spectrum rights, services and distribution. RKLB plus IRDM is marked in green on merchant components, owned and operated constellation, spectrum rights and distribution partners. Merchant components stands out because SpaceX shows no position there.
ASTS and SpaceX are the other names in the table with spectrum access, but ASTS spends 66.0% of revenue on capex in 2028E, which I cover in my ASTS space-based cellular analysis. Planet is another company with its own constellation, and I broke down its data business in my Planet Labs analysis.
Owning several layers means Rocket Lab can sell to customers at more than one point and keep more of the value inside the company. A pure launch company or a pure satellite company can’t do that.
Market Size and the Medium and Large Rocket Race
Because Rocket Lab spans launch, spacecraft, components and services, its addressable market is wider than a launch only business. Neutron is what moves it into the medium and large rocket class, where SpaceX has dominated. (For a closer look at the incumbent, see my SpaceX (SPCX) breakdown on reusable launch and Starlink.) If Neutron reaches the cadence in the chart, Rocket Lab becomes a credible rival there, not just the small launch specialist.
What Could Go Wrong
SpaceX is projected to grow faster, with a 108.0% CAGR from 2025 to 2028 against 25.0% for RKLB, and at a higher 2028E EBITDA margin of 66.8%. Neutron also has to launch on schedule and ramp as planned, and the cost chart depends on that. Neutron has already slipped once, after a tank rupture in January 2026, as covered in my Rocket Lab stock analysis. Rocket Lab’s edge is capital efficiency and breadth, not raw growth.
Final Thoughts on Rocket Lab vs SpaceX
The case for RKLB stock rests on vertical integration, falling Neutron costs and a package that covers more of the value chain than most rivals. Rocket Lab doesn’t need to beat SpaceX everywhere. It needs to execute on Neutron and keep its costs low.
Scalable Space Access & End to End Mission Solutions
Rocket Lab USA, Inc. (NASDAQ: RKLB)
What the company does
Rocket Lab started as a small launch company. Its Electron rocket is the most frequently flown small orbital rocket in the industry. The business has since expanded well beyond launch. It now builds satellites, satellite components, solar cells, optical communication terminals, and space robotics. It also runs two rocket programs. The goal is to be an end to end space company, selling everything from satellite hardware to the launch itself.
The pivot, short term and long term wins
Short term, the pivot has been about acquisitions. Rocket Lab buys specialist suppliers and scales their production using its own manufacturing playbook. These acquisitions target higher margin work, often in the thirty to forty percent gross margin range. This is already showing up in results. The satellite and components segment, called Space Systems, is growing faster than the launch segment.
Long term, the goal is bigger. Rocket Lab wants to reduce dependence on outside suppliers for critical, supply constrained components. This mirrors the model SpaceX used. If it works, Rocket Lab stops being a launch provider and becomes a full space prime, similar to Lockheed or Raytheon. The clearest sign of this ambition is the announced intent to acquire Iridium Communications. That deal is backed by a 3.6 billion dollar bridge loan and is expected to close in 2027.
Technology, short term progress
Neutron, the company’s new medium lift reusable rocket, is the main technology story. Its fairing system, called Hungry Hippo, has completed all testing and subsystem integration. The company has completed hundreds of Archimedes engine hot fires. First stage tank production is underway. The program has moved from component testing to assembling actual flight hardware.
Technology, long term progress and goals
The long term goal is reusability at scale. After debut, management plans a cadence of one launch in year one, three in year two, and five in year three. They have said they hope to beat that pace. For comparison, Electron completed 21 launches in 2025, after debuting in 2017. Reusable rocket cadence tends to accelerate quickly once proven.
Is Neutron on schedule
Not fully. A first stage fuel tank ruptured during a pressure test in January 2026. That pushed the debut from mid year to late 2026. The company still targets a fourth quarter 2026 debut. Pad delivery work is tracking toward that target. Hardware milestones are being hit. The overall calendar has slipped more than once.
Vertical manufacturing through acquisitions
Rocket Lab has bought companies to bring key satellite components in house instead of relying on outside vendors. Timeline of major deals:
SolAero (2022): space grade solar cells, 80 million dollars
GEOST (2025): electro optical and infrared defense payloads, 275 million dollars
Mynaric (2025 to 2026): laser communication terminals, 75 million dollars
Motiv Space Systems (2026): space robotics and precision mechanisms
Each deal adds one more piece of the satellite stack that Rocket Lab now controls directly.
Financial status
Second quarter 2026 revenue was a record 234.1 million dollars. That is up 62 percent year over year and 16.8 percent quarter over quarter. First quarter 2026 revenue was 200.3 million dollars, up 63.5 percent year over year, the first time revenue crossed 200 million dollars. Guidance for third quarter 2026 is 250 to 265 million dollars, another expected record.
EPS progress
GAAP EPS was negative 8 cents in Q2 2026, versus negative 7 cents in Q1 2026. The small decline was mostly due to costs from integrating Mynaric.
QoQ and YoY revenue progress, summarized
Q1 2026: 200.3 million dollars, up 63.5 percent YoY, up 11.5 percent QoQ
Q2 2026: 234.1 million dollars, up 62 percent YoY, up 16.8 percent QoQ
Q3 2026 guidance: 250 to 265 million dollars
Cashflow and EBITDA
Net loss improved to 49.3 million dollars in Q2 2026, down from 66.4 million dollars a year earlier. Adjusted EBITDA loss for the first half of 2026 was 20.6 million dollars, a large improvement from a 57.5 million dollar loss in the first half of 2025. Both net loss and EBITDA loss are shrinking year over year.
Free cash flow is still negative and has not improved sequentially. It was a use of 110.1 million dollars in Q2 2026, worse than the 77.4 million dollar use in Q1 2026. The increase is mostly tied to spending on additional Neutron vehicles beyond the first flight.
Capex and cash runway
Capital expenditures for the first half of 2026 totaled 53.1 million dollars. Spending is expected to stay elevated through Neutron testing, production, and infrastructure buildout. Total liquidity, including cash, marketable securities, and restricted cash, was about 2.4 billion dollars at the end of June 2026. That is up from 828 million dollars at the end of 2025, boosted by capital raises tied to the Iridium deal. Funding does not appear to be a near term constraint.
Path to profitability
Management’s framework is specific. They expect positive adjusted EBITDA in the quarter following a successful Neutron test flight. They expect positive free cash flow roughly 18 to 24 months after that, as more reusable boosters are built and flown. This does not include Iridium, which management expects to add free cash flow immediately once that deal closes.
Backlog and near term guidance
Backlog reached 2.36 billion dollars at the end of Q2 2026, up 137 percent year over year. This figure does not include more than 800 million dollars in new contracts signed after quarter end, which will appear in the next report. Combining backlog with contracts signed since, Rocket Lab has roughly three years of forward revenue already secured.
Longer term analyst estimates
Wall Street consensus revenue estimates, as of the latest data, show a steep multi year growth curve:
Note that the number of analysts covering later years drops sharply, so anything past 2029 should be treated as a rough directional estimate, not a firm forecast.
On earnings, consensus EPS is expected to stay negative through 2026 at negative 4 cents, then turn positive in 2027 at 5 cents. From there, estimates show a steady climb: 38 cents in 2028, 64 cents in 2029, and 1.01 dollars in 2030. That timeline lines up closely with management’s own guidance that profitability follows Neutron’s first successful flight and subsequent fleet buildout.
Analyst ratings and price targets
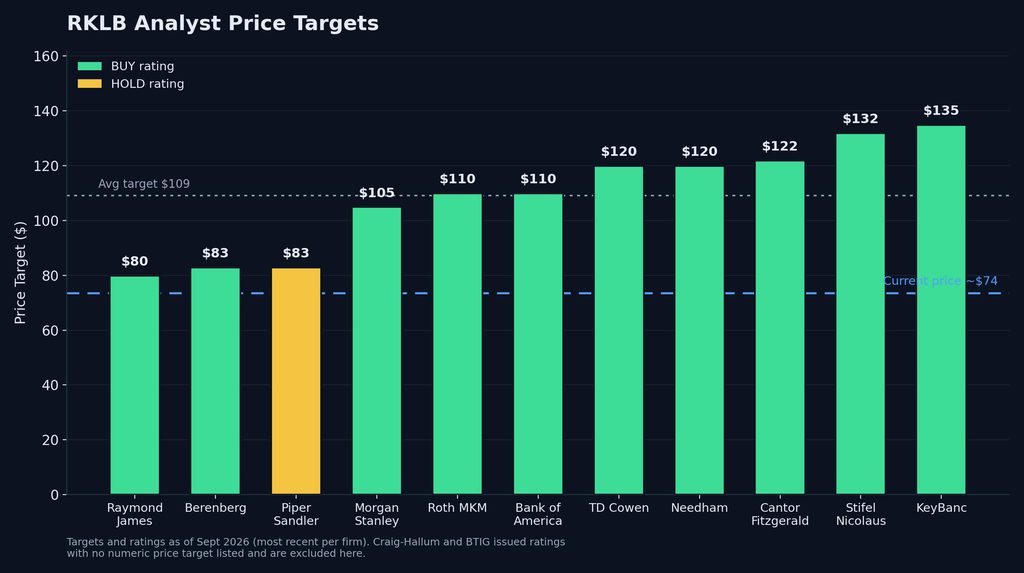
Coverage has grown recently, and the tone is mostly positive. Of the analyst actions in the past several weeks, the large majority are BUY ratings, with only BTIG and Piper Sandler at HOLD. Price targets range widely, from 80 dollars at Raymond James to 135 dollars at KeyBanc. Several firms raised their targets in August, including Cantor Fitzgerald, which moved from 96 to 122 dollars. A couple, Bank of America and Roth MKM, actually lowered their targets while keeping BUY ratings. Based on the upside percentages listed alongside these targets, the stock was trading around 74 dollars at the time these ratings were issued.
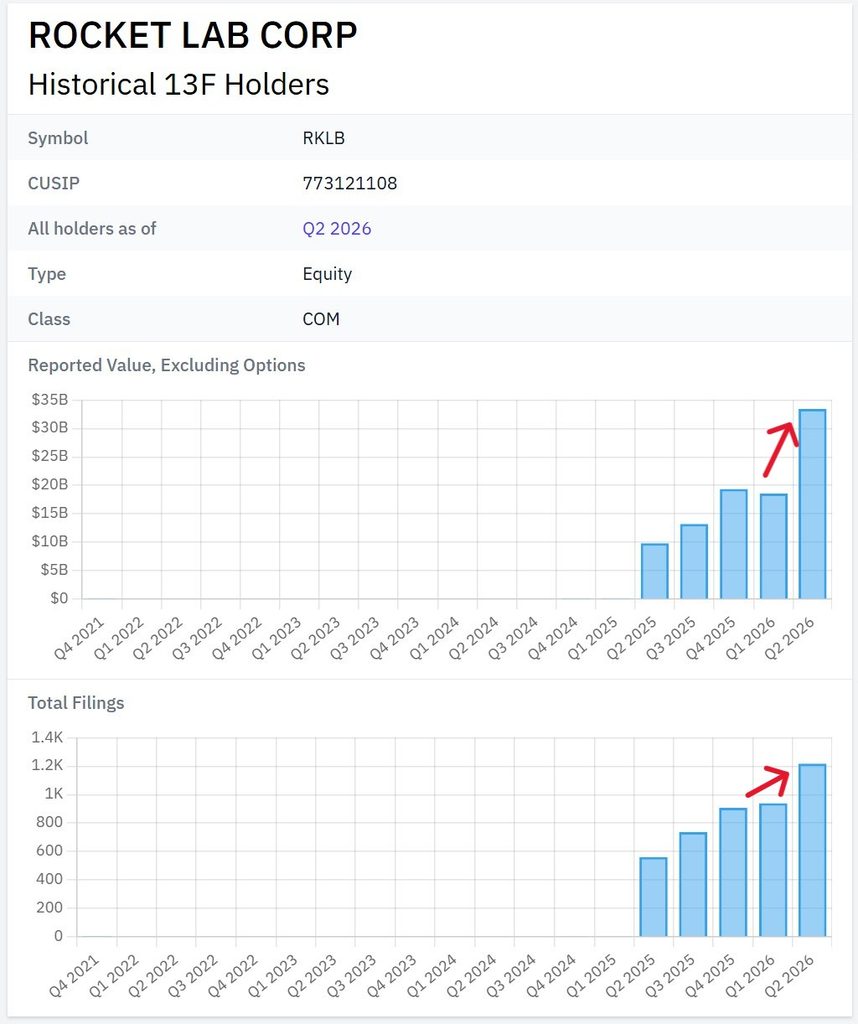
Fresh 13F filings show a sharp jump in institutional buying
The most recent quarterly filings add real weight to that institutional trend. Total 13F reported value in RKLB jumped from about 18 billion dollars in the first quarter of 2026 to roughly 33 billion dollars in the second quarter, and the number of institutions filing on the stock climbed from about 920 to around 1,200 in that same quarter. Both numbers had been growing steadily for a year, but this was the sharpest single quarter jump yet.
Two positions stand out. California State Teachers Retirement System, one of the largest public pension funds in the country, increased its stake from 735,075 shares to 80.5 million shares in a single quarter, an increase of more than 10,800 percent, making it one of the largest holders of the stock. Norges Bank, which manages Norway’s sovereign wealth fund and is one of the largest institutional investors in the world, opened a brand new position of 5.4 million shares. Around the same time, T. Rowe Price, Allianz, Wellington Management, and Nomura all initiated new positions, and existing holders including Goldman Sachs, Invesco, and JPMorgan added significantly to what they already owned.
It is not one directional though. Baillie Gifford, previously one of the larger holders, cut its position by 44 percent in the same quarter, and Geode Capital trimmed slightly. So while the overall trend is clearly toward more institutional buying, not every large holder is on the same side of the trade.
Why this company may be worth investing in
The core bet is that Rocket Lab can achieve vertical integration in space the way SpaceX did. Almost no company outside SpaceX has managed this. If Neutron flies reliably and reusability economics hold, Rocket Lab becomes a lower cost alternative to Falcon 9 for medium lift missions. This comes as demand for satellite constellation and defense launches is increasing. The satellite manufacturing business is already growing faster than launch. Backlog covers years of revenue. Cash position is strong enough to fund the buildout without urgent capital needs. Analyst sentiment currently backs this thesis, with most active ratings at BUY and price targets well above where the stock traded when those calls were made.
The moat
Three factors support it. First, Electron’s launch record has earned trust from government and defense customers, who do not switch vendors easily. Second, vertical integration means Rocket Lab controls solar cells, optical terminals, robotics, and payload technology in house, making it harder for competitors to undercut on cost or supply chain risk. Third, deep relationships with agencies like the Space Force matter as defense space spending grows, including programs tied to missile defense.
Risks
Neutron has slipped multiple times. Cash burn remains heavy. The company is absorbing several large acquisitions at once, plus the pending Iridium deal. Profitability, per both management guidance and analyst estimates, remains a 2027 story, not a 2026 one. Long range revenue estimates rely on very few analysts and should be treated with caution. The outcome depends heavily on Neutron flying, and flying reliably, in the near term.
Disclosure: The author holds a long position in $RKLB stock at the time of writing
The Space Data Center Powering Tomorrow’s Geospatial Intelligence
Planet Labs PBC (NYSE: PL)
Planet Labs is a leading provider of global daily satellite imagery and geospatial intelligence, operating the largest constellation of Earth-observation satellites in history. Specifically, by functioning as a continuous space data center, the company captures daily high-resolution imagery of Earth’s entire landmass, ultimately delivering actionable data analytics and AI-driven insights for commercial enterprise, defense, and environmental monitoring.
Competitive Advantage & Structural Moat
First and foremost, building an economic moat in Earth observation requires scaling hardware, securing persistent orbital bandwidth, and accumulating time-series data. As a result, Planet Labs PBC ($PL) maintains a structural competitive advantage anchored in proprietary hardware deployment and data capture.
Unlocking Value Through Decades of Earth Data
To begin with, Planet captures daily, high-resolution imagery across Earth’s entire landmass, thereby creating a multi-petabyte time-series archive of global change dating back years. Although competitors can build and launch satellites today, they cannot go back in time to collect historical data. Consequently, this growing data repository functions like an orbital data bank, serving as an irreplaceable baseline for computer vision models, geospatial machine learning, and temporal analysis.
Agile Aerospace Manufacturing
In contrast, traditional satellite defense contractors rely on high-cost, customized hardware built over multi-year timelines. Instead, Planet pioneered an agile aerospace model using commercial off-the-shelf components to design, build, and deploy low-cost CubeSats. Furthermore, this manufacturing efficiency enables rapid iterative hardware upgrades directly in orbit, ultimately keeping capital expenditure far below legacy satellite operators.
Synergistic Multi-Constellation Ecosystem
Additionally, Planet operates hundreds of satellites across complementary orbital roles:
PlanetScope (Doves): Continuous line-scanning of all global landmasses at medium resolution.
SkySat and Pelican: High-resolution tasking assets deployed for targeted site inspection.
Tanager: Hyperspectral imaging tracking point-source gas emissions.
Together, these systems trigger automated tip and cue workflows. For example, a change detected by the daily global scan automatically triggers a high-resolution target tasking request without human intervention.
High Customer Switching Costs
Meanwhile, enterprise clients, defense agencies, and agricultural operators integrate Planet’s continuous API feeds directly into their daily supply chain, risk assessment, and intelligence platforms. Therefore, swapping to an alternative data provider disrupts custom algorithmic models trained on Planet’s specific spatial and temporal datasets, ultimately locking in long-term enterprise subscription revenues.
Key Structural Vulnerabilities
However, several risks remain:
Capital Intensity: Maintaining orbital fleets demands ongoing rocket launches and capital deployment to replace de-orbiting hardware.
Commercialization Timeline: Monetizing raw spatial data into high-margin software analytics requires scaling sales execution across non-defense sectors.
If you have been following space tech or telecom investing recently, you’ve likely seen AST SpaceMobile ($ASTS) dominating financial headlines. What started as a moonshot idea—connecting everyday smartphones directly to satellites in low Earth orbit (LEO)—has morphed into one of the most compelling infrastructure plays of the decade.
With their Q2 2026 earnings delivered and commercial deployment accelerating, let’s break down what the company actually does, its technological progress, financial runway, strategic pivot, and the massive moat it’s building.
1. What Does AST SpaceMobile Do?
In simple terms, AST SpaceMobile is building the first space-based cellular broadband network designed to connect directly to standard, unmodified smartphones.
Unlike legacy satellite phone systems (which require bulky satellite dishes or special hardware), AST SpaceMobile works with the phone in your pocket right now. By partnering directly with Mobile Network Operators (MNOs) like AT&T, Verizon, Vodafone, and Rakuten, ASTS allows telecom giants to fill cellular dead zones globally using their existing spectrum. If you step outside cell coverage, your phone simply connects to a satellite overhead without requiring a single setting change.
2. The Strategic Pivot: From Smallsat Maker to Global Telecom & Defense Giant
One of the biggest drivers behind ASTS’s multi-year turnaround was its strategic pivot:
Short-Term Pivot: The company divested non-core assets (such as selling its majority stake in smallsat builder NanoAvionics) to focus 100% of its engineering and capital on Direct-to-Device (D2D) cellular satellites. Simultaneously, it pivoted toward dual-use government applications, adapting its commercial satellite technology for military secure communications and space-based tactical radar.
Long-Term Pivot: Instead of competing against traditional telecom carriers, AST SpaceMobile pivoted into an infrastructure partner model. By signing revenue-share and prepayment agreements with over 60 MNOs representing 3+ billion subscribers worldwide, ASTS eliminated subscriber acquisition costs and secured commercial lock-in.
3. Technology Progress & Roadmap: Are They On Track?
The Goal: Deploy a global LEO constellation capable of continuous, high-speed 4G/5G voice, data, and video broadband directly to standard mobile devices.
Short-Term Progress: After proving direct-to-cell 2G, 4G, and 5G connectivity with its prototype BlueWalker 3 satellite (achieving high-definition video call capability from space), ASTS launched its initial commercial BlueBird satellites. With 13 spacecraft now in orbit, BlueBirds 14–16 ready for launch, and dozens more in assembly, orbital presence is expanding rapidly.
Long-Term Progress: ASTS is transitioning production to its Block 2 BlueBird satellites. Powered by custom in-house ASIC chips, Block 2 satellites offer up to 10x the processing capacity per satellite with massive ~2,400 sq. ft. phased-array antennas.
Roadmap Tracking:Yes, they are on track. Management is targeting approximately 45 BlueBird satellites in orbit by early 2027, unlocking continuous consumer beta service and full commercial rollouts across core target markets like North America, Europe, and Japan.
4. Financial Health & Operating Metrics
AST SpaceMobile has significantly strengthened its balance sheet to support satellite manufacturing and launch schedules.
Financial Metric
Latest Reported Figure (Q2 2026 / FY 2026)
Strategic Context
Pro Forma Cash & Liquidity
~$3.7+ Billion
Includes $2.7B in Q2 cash + $1.15B convertible note offering in July 2026.
Contract Backlog
~$1.3 Billion
Commercial pre-payments & U.S. government contract awards.
Q2 Revenue Growth
$31.5 Million
More than doubled sequentially (QoQ); up from near zero YoY.
Heavy deployment toward Block 2 satellite production & launches.
EPS Progress
-$0.35 per share
Narrowed year-over-year from -$0.41 in Q2 2025.
Cash Flow, Burn Rate & Path to Profitability
Cash Flow & EBITDA State: Operating cash flow remains negative due to front-loaded CapEx for constellation construction. However, cash inflows are benefiting from MNO partner prepayments (such as stc group’s $175M agreement) and milestone-based U.S. government defense awards.
Cash Runway: With over $3.7 Billion in total liquidity, ASTS has fully funded its initial 45-satellite deployment into 2027+ without requiring near-term dilutive capital raises.
Timeline to Profitability: ASTS expects high-margin commercial service revenue to begin scaling late 2026 into 2027. As satellite operating margins typically exceed 80–90% once in orbit, the company is positioned for operational EBITDA inflection as commercial beta launches in 2027.
5. Institutional Ownership Shift: Wall Street Takes Notice
Three years ago, ASTS was largely a retail-driven speculative stock with institutional ownership sitting around 10–15%.
Today, institutional ownership has surged to over 55%–60%. Major global asset managers (including BlackRock, Vanguard, and tier-1 telecom venture funds) have accumulated nearly 100 million shares, confirming that institutional investors now view space-based cellular as a validated mainstream asset class.
6. The Investment Thesis & Economic Moat: Why ASTS?
Why is AST SpaceMobile commanding a premium valuation? Its competitive moat is built on four pillars:
Massive Patent Wall: Over 3,400 patent and patent-pending claims protecting their complex phased-array antenna technology and direct-to-cell signal processing.
No Extra Hardware Required: Competitors often require ground terminals or special satellite chips. ASTS works directly on standard iPhones and Android devices.
MNO Spectrum & Distribution Network: ASTS does not need to buy costly spectrum; it uses the licensed cellular spectrum of its MNO partners. This yields immediate access to 3B+ potential customers overnight.
Dual-Use Defense Strategy: Growing U.S. and allied government defense contracts create a stable, non-dilutive baseline revenue stream alongside commercial consumer operations.
The Bottom Line
AST SpaceMobile has transitioned from a high-risk engineering proof-of-concept into a fully capitalized telecommunications infrastructure platform. With $3.7B+ in liquidity, commercial revenue ramping rapidly toward its $150M–$200M target, and satellite deployments on schedule for 2027,$ASTS stands out as a category-defining leader in global connectivity.
Disclosure: The author holds a long position in $ASTS stock at the time of writing