IREN Limited (NASDAQ: IREN)
Inside IREN’s $30 Billion Bet: How a Bitcoin Miner is Building the Future of AI
If you haven’t been paying attention to the data center space lately, you might still think of IREN Limited (formerly Iris Energy) as just another crypto mining stock. But behind the scenes, this company is pulling off one of the most aggressive and fascinating business pivots in modern tech.
Let’s break down exactly what IREN is doing right now, how their technology and financials are tracking, and whether their massive gamble is actually worth your investment.
What Does This Company Actually Do?
At its core, IREN builds, owns, and operates next-generation data centers. Originally, they made their money by plugging thousands of high-powered computers into 100% renewable energy sources to mine Bitcoin.
However, they realized that the exact same infrastructure needed for Bitcoin mining—massive power capacity, advanced cooling, and cheap electricity—is exactly what the world desperately needs for Artificial Intelligence. Today, IREN is rapidly transitioning from a pure-play Bitcoin miner into a massive, tier-one AI Cloud infrastructure provider.
The Pivot: Successes and the Hidden “Moat”
The Short-Term Success: IREN just crossed a massive psychological and financial milestone. In their fiscal fourth quarter of 2026, their AI Cloud Services revenue hit $70.5 million, officially eclipsing their Bitcoin mining revenue ($66.7 million) for the very first time. They also locked in staggering partnerships, including a $9.7 billion cloud contract with Microsoft and a potential multi-gigawatt deployment with NVIDIA.
The Long-Term Success: IREN is successfully shaking off the volatile “crypto stock” label to become a foundational pillar of the AI boom.
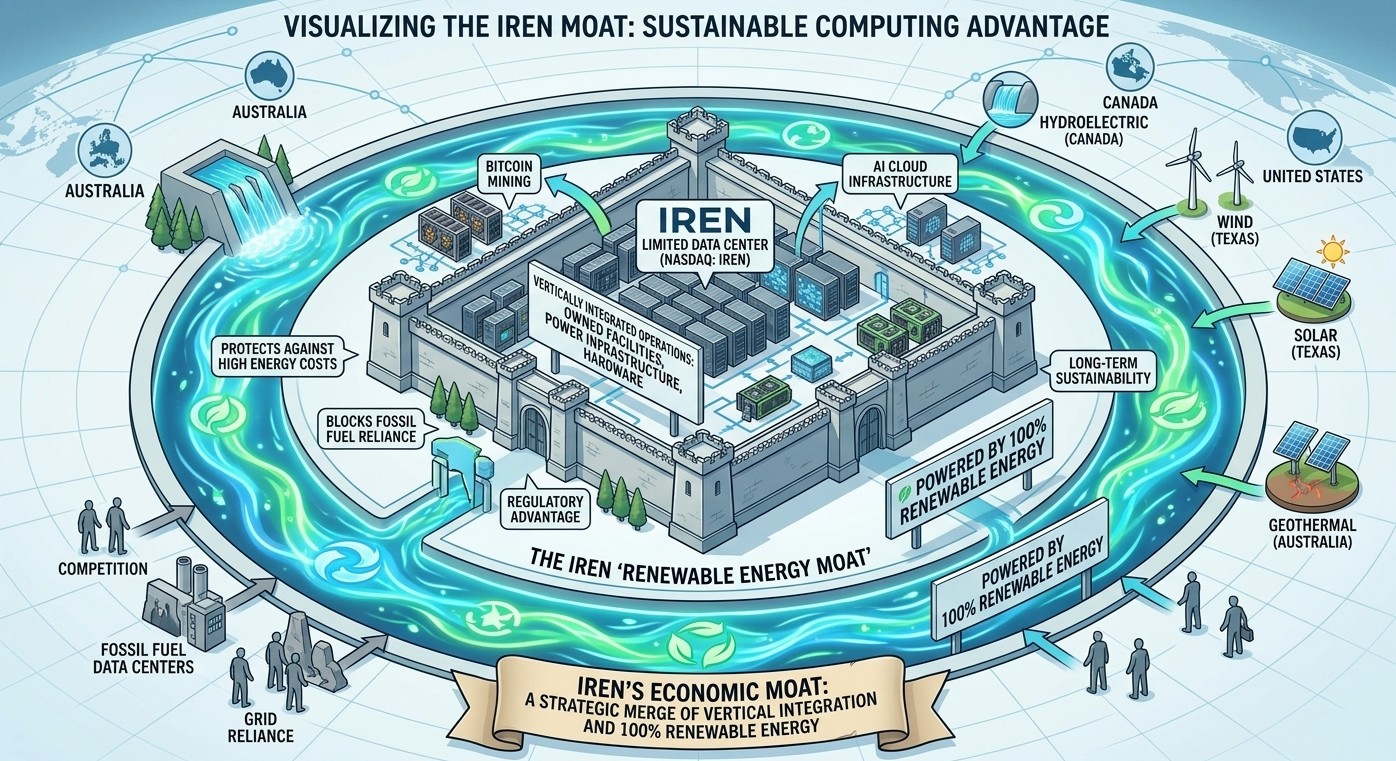
The Moat: In the AI world, the biggest bottleneck isn’t getting computer chips; it’s getting electricity. IREN’s ultimate moat is its access to ridiculously cheap, 100% renewable energy (averaging roughly $0.033/kWh) and their pre-existing grid connections. While traditional tech companies are waiting years for utility companies to approve grid hookups, IREN already has the power flowing and has secured a pipeline of roughly 5 Gigawatts (GW) of grid connections for future deployments.
Technology Progress and the Roadmap
Short-Term Progress: Right now, IREN is operating about 40 Megawatts (MW) of AI Cloud capacity, while still running 23.2 Exahashes per second (roughly 380MW) of Bitcoin mining equipment. They’ve recently acquired companies like Nostrum and Mirantis to instantly beef up their software capabilities and expand their physical footprint into Europe.
Long-Term Progress & Goals: Their ultimate goal is to transition the vast majority of their power capacity away from crypto and into high-margin AI compute. They are aiming for substantial completion of this massive transition by December 31, 2026.
Are they on track? Absolutely. They are executing flawlessly on the physical build-out, purposefully decommissioning older Bitcoin miners to make physical space and free up electricity for incredibly lucrative AI GPU clusters.
The Official Guidance: Short and Long Term
When management released their recent FY2026 report, they laid out crystal clear guidance for what investors should expect over the next 18 to 24 months.
- Short-Term (End of 2026): The immediate catalyst is that their 2026 AI compute capacity is already effectively sold out. Their strict deadline is to completely decommission all remaining Bitcoin mining operations by December 31, 2026, delivering roughly 300 Megawatts (0.3GW) of pure AI IT load. Financially, management expects their contracted Annual Recurring Revenue (ARR) to rocket from the $1 billion operating today to over $4 billion by the end of December. Be prepared for a short-term hit to operating margins: cash SG&A costs are expected to jump $40–$50 million next quarter as they aggressively hire to manage the AI transition.
- Long-Term (2027 and Beyond): For 2027, IREN is targeting 800 Megawatts (0.8GW) of cumulative delivery, pushing toward a gross AI capacity of 1.2 Gigawatts. They are currently in late-stage negotiations to lock in new customers for that upcoming 2027 capacity. To fund the $25 to $30 billion in planned CapEx, they have already lined up roughly $14 billion via cash, customer prepayments, and existing GPU financing, and are actively targeting another $8 billion in new asset-backed financing. Zooming out further, they are developing a multi-year global pipeline of over 5 Gigawatts of secured grid connections to support next-generation, liquid-cooled data centers globally.
The Financial Reality: Cash, Burn, and a $30 Billion Bill
This is where the story gets both terrifying and exhilarating. Pivoting to AI is not cheap.
- CapEx (Capital Expenditure): IREN management dropped a bombshell on their recent earnings call, issuing fiscal 2027 CapEx guidance between $25 billion and $30 billion. This money is needed to buy massive amounts of GPUs and build out the physical data centers.
- Cash Status & Runway: How on earth does a company fund that? Over the last 12 months, IREN has secured roughly $19 billion in funding, including a massive $3.6 billion investment-grade facility backed by their Microsoft contract. They ended FY2026 with roughly $5.89 billion in unrestricted cash.
- Debt: To fund this, long-term debt skyrocketed from under $1 billion to over $7.4 billion in just 12 months.
- Path to Profitability: Because they are spending money faster than they make it to build out this infrastructure, true bottom-line profitability will take time. They posted a net loss in FY2026, driven largely by non-cash impairments as they write down old crypto hardware. They currently have about $4 billion in contracted annual recurring revenue (ARR) lined up for their AI capacity, which will dictate their cash flow generation as these centers come online.
Revenue, EBITDA, and EPS Growth
Let’s look at the actual operational numbers for Fiscal Year 2026:
- YoY Revenue: Excellent. Full-year revenue jumped 41.2% year-over-year, from $501 million to $707 million.
- QoQ Revenue: Q4 2026 total revenue dipped slightly to $137.2 million (from $144.8 million in Q3). However, the AI portion of that revenue more than doubled sequentially, growing from $33.6 million to $70.5 million in a single quarter.
- EBITDA & Cashflow: Operating cash flow is strong thanks to high hardware gross margins, but full-year adjusted EBITDA actually slipped by 8.9% (down to $245.7 million). This is a natural side effect of the heavy transition costs of shifting the business model.
- EPS (Earnings Per Share): EPS took a beating. Thanks to massive non-cash impairment charges and heavy share dilution to raise cash, FY2026 EPS fell to $(2.22), down from a positive $0.39 the year prior.
Institutional Confidence & Wall Street Price Targets
If you want to know if a company’s vision is believable, follow the “smart money.” Over the last few years, institutional investors have aggressively bought into IREN’s pivot. In the last 12 months alone, institutions have poured $3.03 billion into the stock, compared to just $662.5 million in outflows. Today, institutional ownership sits at a very healthy 41%.
Following IREN’s latest earnings report, major Wall Street research firms overwhelmingly reiterated bullish ratings and aggressive price targets, projecting upside potential exceeding 180%:

The Verdict: Why is it Worth Investing?
Investing in IREN right now is a high-risk, high-reward execution play.
It is worth investing because the market is still catching up to the pivot. Because IREN still mines Bitcoin, many retail algorithms and traditional investors treat it like a volatile crypto stock. However, when you look at their $4 billion in contracted AI revenue and institutional support from firms like Bernstein and Cantor Fitzgerald setting target prices near $100, the upside potential is massive.
If management can manage the massive $30 billion debt and CapEx load without drowning, IREN is positioned to be one of the premier landlords of the AI revolution.
Disclosure: The author holds a long position in $IREN stock at the time of writing